Alternative Investments: What to Know Before You Dive In
Alternative investments have moved from niche strategy to mainstream conversation. More individual investors than ever are asking whether they should add something beyond traditional stocks and bonds to their portfolios. Before you jump in, it’s essential to understand not only the potential rewards, but also the risks, time horizons, and practical steps involved.
This guide will help you decide whether alternative investments fit your goals, how to approach them thoughtfully, and what questions to ask before committing your money.
What Are Alternative Investments?
In simple terms, alternative investments are any assets that are not conventional stocks or bonds. They can be tangible or intangible, simple or complex, and privately or publicly traded.
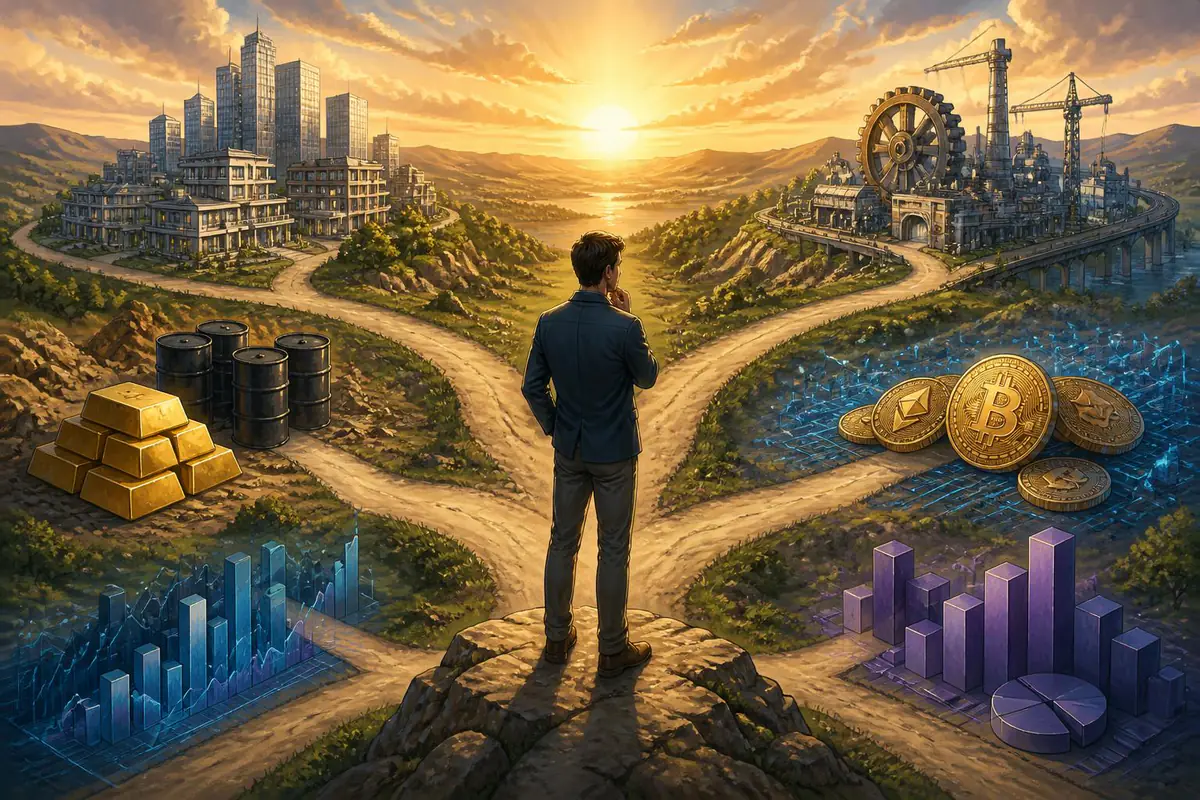
Common types of alternative investments include:
- Real estate (residential, commercial, or land)
- Private equity and venture capital
- Hedge funds and fund-of-funds
- Commodities (gold, oil, agricultural products)
- Infrastructure (toll roads, utilities, renewable energy assets)
- Collectibles (art, classic cars, wine, rare coins)
- Digital assets (cryptocurrencies, tokenized securities)
Each category has its own rules, risks, and return profile. They share a common theme: they often behave differently from traditional public market assets, which can be useful—but also challenging.
Why People Are Drawn to Alternatives
Investors rarely wake up and decide to buy an unfamiliar asset for no reason. There are specific benefits that make alternatives appealing, especially in uncertain markets.
Key potential advantages include:
- Diversification benefits across asset classes: Because many alternatives don’t move in lockstep with stock markets, they can reduce overall portfolio volatility.
- Inflation protection: Real assets like real estate and commodities often rise in value when prices in the broader economy increase.
- Enhanced return potential: Private equity, venture capital, and some hedge fund strategies aim to outperform typical public markets over long periods.
- Access to unique opportunities: Alternatives can give exposure to niche markets and private companies unavailable on public exchanges.
These benefits are real—but they’re not guaranteed. They come with meaningful trade-offs, which you should understand before putting your savings at risk.
Key Risks You Cannot Ignore
Every investment has risk, but alternatives often bundle several types of risk together. Ignoring them can turn a promising opportunity into an expensive lesson.
Some of the most important risks include:
Illiquidity risk: Many alternatives cannot be easily sold. You may be locked in for years, especially with private equity, venture funds, or certain real estate deals. If you might need your money soon, illiquid investments can be dangerous.
Complexity risk: Structures like hedge funds, limited partnerships, and derivative-based strategies can be hard to fully understand. If you can’t clearly explain how the investment makes money and what could make it lose money, proceed with caution.
Valuation uncertainty: Public stocks have prices updated every second. Private assets often use appraisals, models, or infrequent transactions. That means reported values may lag reality—especially during market stress.
Higher fee levels: Many alternative strategies charge management fees plus performance fees. These can significantly reduce your net returns over time. A good question to ask is: “What performance is needed just to justify these fees?”
Regulatory and counterparty risk: Some alternatives operate in less regulated spaces, or rely on specific companies and partners. If a fund shuts down, an exchange collapses, or a partner fails, you could face delays or permanent losses.
Are Alternatives Right for You? A Self-Check
Before diving into any alternative investment, take an honest look at your situation. Consider the following areas carefully.
| Factor | What to Ask Yourself |
|---|---|
| Time Horizon | Can I truly commit this money for 5–10 years without needing it? |
| Risk Tolerance | How would I feel if this investment dropped 50% on paper? |
| Liquidity Needs | Do I have enough in easily accessible savings and public markets? |
| Knowledge Level | Do I understand the asset, strategy, and main risks clearly? |
| Diversification | Will this complement, not duplicate, what I already own? |
If your answers reveal that you need quick access to cash, dislike short-term volatility, or don’t have time to research thoroughly, it may be better to start small or stay with simpler options.
How to Evaluate an Alternative Investment
Once you’ve decided that alternatives might fit, the next step is choosing specific opportunities. A disciplined evaluation process can help you avoid emotional decisions and marketing hype.
Practical steps to analyze an opportunity include:
1. Understand the strategy
Ask how the investment intends to generate returns. Is it collecting rent, improving and selling businesses, arbitraging price differences, or something else? If the explanation relies heavily on jargon or feels vague, that’s a warning sign.
2. Map the risks and scenarios
List what could go wrong: economic downturns, regulatory changes, rising interest rates, operational failures. For each risk, consider the likely impact and whether you are comfortable with downside outcomes.
3. Scrutinize fees and lock-ups
Compare the fee structure to similar products. Understand when and how you can redeem your money. Some funds limit withdrawals during stress, just when you might want liquidity most.
4. Assess the manager’s track record
Look for consistent performance across different market environments, not just one good year. Ask about the team’s experience, transparency, and how they personally invest alongside clients.
5. Start with a small allocation
Even if everything looks attractive, consider beginning with a modest amount. Use the first year or two to learn how the investment behaves in your overall portfolio.
Practical Ways to Get Started
You don’t have to be ultra-wealthy to access alternatives anymore. There are multiple entry points that allow for measured exposure with reasonable minimums.
Some accessible paths include:
- Publicly traded REITs or real estate funds for exposure to property markets.
- Listed commodity funds that track gold, energy, or broad commodity indices.
- Interval funds and listed closed-end funds that offer partial liquidity.
- Regulated alternative strategy funds that mirror hedge fund approaches with more transparency.
If you’re exploring private deals—like a friend’s startup or a local real estate syndicate—be doubly cautious. Personal relationships can cloud judgment. Review documents carefully, and don’t skip professional advice just because you know the people involved.
Building a Sensible Allocation Plan
Even if you’re excited about alternatives, they should usually be a complement, not a replacement, for diversified stock and bond holdings.
Many individual investors keep alternatives as a moderate slice of their total portfolio. For some, that might be 5–10%; for others with high risk tolerance, perhaps 15–25%. The right number depends on your goals, age, income stability, and comfort with illiquidity.
A thoughtful process could look like this:
- Clarify your long-term goals (retirement, education, financial independence).
- Design a core portfolio of diversified public assets first.
- Decide what problems you want alternatives to solve (e.g., inflation hedge, income, diversification).
- Allocate gradually, reviewing outcomes annually rather than chasing short-term performance.
Review your entire portfolio at least once a year. If alternatives grow to a larger share than planned—due to strong performance—rebalance thoughtfully to keep risk aligned with your original intentions.
Red Flags to Watch For
Some warning signs are common across many questionable alternative investments. Be extremely careful if you see:
Promises of high returns with “little or no risk,” pressure to invest quickly, vague or inconsistent documentation, opaque fee structures, or limited ability to ask questions and receive clear answers.
Trust your instincts. If something feels off, step back. There will always be another opportunity; your capital is finite.
Using Professional Guidance Wisely
You don’t need to become an expert overnight, but you do need to be an informed decision-maker. A qualified financial planner, tax professional, or investment advisor can help you:
Understand how a specific alternative fits into your bigger picture, identify hidden risks or conflicts of interest, evaluate whether fees and structures are fair, and create an allocation plan that matches your personal risk profile.
Even when working with professionals, remember that it is your money and your future. Ask questions until you feel confident. A good advisor welcomes informed, persistent questioning.
Moving Forward with Clarity and Confidence
Alternative investments can be powerful tools for diversification, inflation protection, and potentially higher long-term returns. They can also be sources of stress if you leap in without understanding the commitments involved.
Approach them with curiosity, discipline, and humility. Start from a strong core portfolio, keep allocations reasonable, and insist on transparency. When you combine clear goals with patient discipline, alternatives can support—not disrupt—your path toward long-term financial security.