Budgeting That Actually Works: Simple Systems You Can Stick With
Most people don’t fail at money because they are bad at math. They struggle because traditional budgeting feels confusing, restrictive, or too time-consuming to maintain. The good news is that you can build a simple money system that fits your real life, even if you’ve failed at budgeting before.
This article will walk you through practical, low-stress methods to manage your money, stay consistent, and still enjoy your life along the way. You don’t need complex spreadsheets or perfect discipline. You just need a system that’s easy to follow, forgiving when you slip, and clear enough to show you what to do next.
Step 1: Get Clear on What You Actually Want
Before any numbers, you need a reason. A budget without a purpose feels like punishment. A budget with a purpose feels like a plan. Take a few minutes to define what you want your money to do for you in the next 6–12 months.
Instead of vague intentions like “save more,” aim for specific, emotionally meaningful goals, such as:
- Build a $1,000 starter emergency fund.
- Pay off a high-interest credit card.
- Stop living paycheck to paycheck.
- Save for a short, stress-free weekend trip.
Write down your top three. These are your short-term money priorities. Your budget will become the tool to move you toward them, not just a list of things you can’t do.
Step 2: Take a Gentle Snapshot of Your Money
You do not need a perfect historical record to start. You just need a clear picture of what is happening right now. Think of this as a snapshot, not an audit.
Gather this basic information:
- Monthly income after taxes from all sources.
- Fixed expenses: rent, utilities, minimum debt payments, insurance.
- Flexible spending: groceries, eating out, transportation, fun.
If you don’t know your exact flexible spending amounts, estimate using the last month from your banking app. Imperfect numbers are fine. You can refine them later as you track.
From here, calculate a simple overview:
| Category | Amount (Monthly) |
|---|---|
| Total Take-Home Income | $________ |
| Fixed Essentials | $________ |
| Minimum Debt Payments | $________ |
| Flexible / Daily Spending | $________ |
| Leftover (or Shortage) | $________ |
That last line tells you a lot. If you have money left over, you can assign it to goals. If you are short, you now know you need to adjust spending, increase income, or both. Clarity is the first win.
Step 3: Choose a Budget Style That Fits You
The best budget is the one you will actually use. Different personalities thrive with different systems. Instead of forcing yourself into a complicated method, pick a style that feels natural.
Here are three simple budgeting approaches that work for most people:
1. The 50/30/20 Guideline
Ideal if you want structure without too much detail.
You divide your take-home income:
- 50% to needs (rent, utilities, groceries, transport).
- 30% to wants (dining out, entertainment, non-essentials).
- 20% to savings and debt payoff.
If your situation is tight, your percentages may not match exactly. That’s fine. The goal is to give you a simple target and help you see which area is squeezing you.
2. The Two-Account “Automatic” Budget
Great if you dislike tracking and love autopilot.
Set up at least two main accounts:
One account for bills and responsibilities. Route enough money here to cover all fixed expenses plus minimum debt payments.
A second account for everyday and fun spending. Whatever is in this account each week is what you can spend without guilt.
Move money automatically on payday. As long as you don’t overspend from the bills account, your obligations are covered.
3. The Cash or Digital Envelope System
Helpful if you often wonder, “Where did all my money go?”
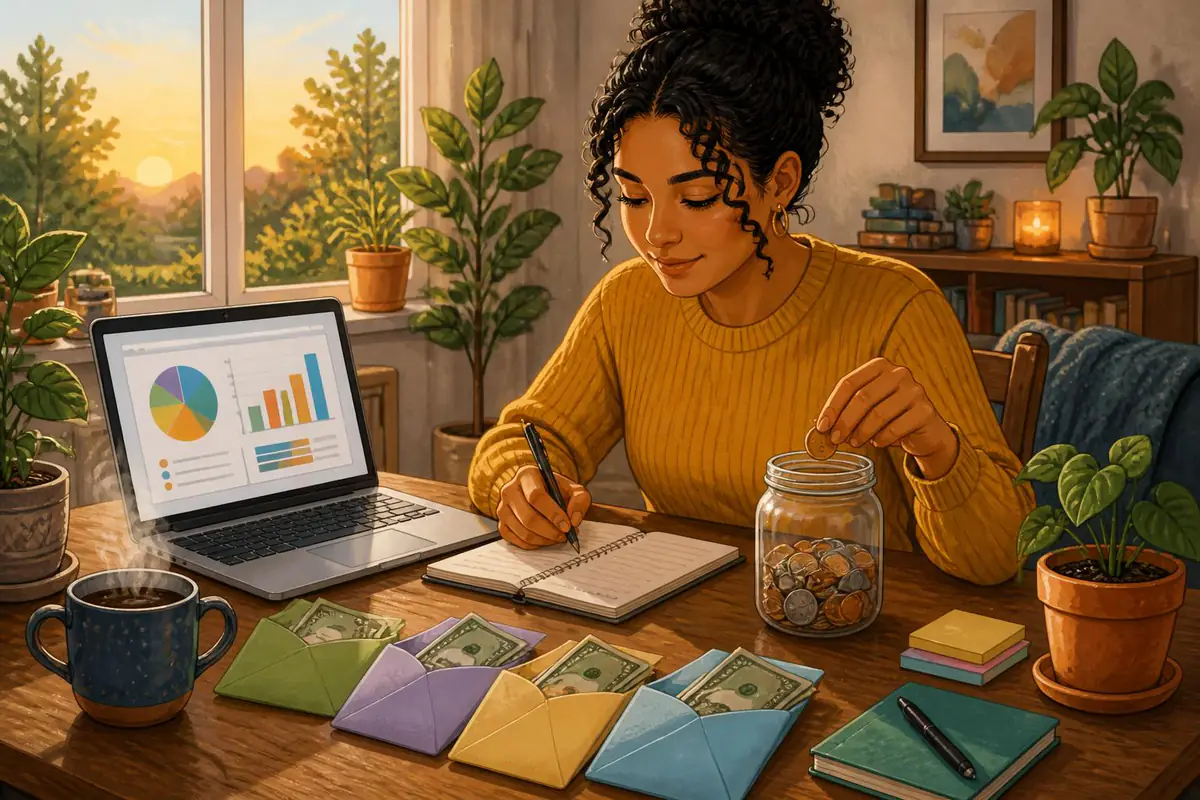
You divide your flexible spending into categories (like groceries, eating out, gas, fun) and give each a set amount per week or month. This can be physical cash in envelopes or digital “buckets” in your banking app.
When an envelope is empty, you stop spending in that category until the period resets. This builds natural awareness and control, without obsessing over every transaction.
Step 4: Build a Weekly Money Ritual (15 Minutes)
Budgeting fails when it’s a once-a-month panic session. Instead, anchor your system with a small, repeatable habit: a weekly money check-in.
Pick a consistent time: Sunday afternoon, Friday evening, or whenever you’re relaxed. In 10–15 minutes, you can:
Review your accounts: glance at your balances and recent transactions.
Check your categories or envelopes: see what’s left for the week.
Compare with your goals: Are you moving money toward your top three priorities?
Decide one small action: maybe transfer $20 to savings, skip one takeout meal, or make an extra $10 debt payment.
This ritual keeps you close to your numbers without letting money stress build up. Consistency beats intensity every time.
Step 5: Design a Budget You Can Actually Stick To
If your budget is so tight that it allows no flexibility, you will abandon it quickly. A workable budget includes both discipline and breathing room.
Use these principles to design yours:
Include real-life fun. Budget something, even a small amount, for enjoyment. A budget with zero fun is a budget you will secretly rebel against.
Expect irregular expenses. Things like car repairs, gifts, annual subscriptions, or medical costs are not emergencies; they are irregular. Estimate what you spend yearly, divide by 12, and set aside that amount monthly in a “sinking fund.”
Protect a starter emergency fund. Even $500–$1,000 can turn a crisis into an inconvenience. Treat this fund as a shield against debt, not as extra spending money.
Start with small changes. Rather than slashing every category, target easy wins: cancel a forgotten subscription, cook at home one extra night a week, or cap ride-share spending.
Step 6: Make Automation Your Ally
The less you rely on willpower, the more reliable your budget becomes. Automation helps your money follow your plan even on days when you are tired, stressed, or busy.
Automate wherever possible:
Set up direct deposit that splits your paycheck into your bills account, spending account, and savings.
Arrange automatic transfers right after payday for savings and debt payments, before you see the money as available to spend.
Use automatic bill pay for fixed expenses to avoid late fees and mental load.
Automation does not replace awareness, but it removes dozens of tiny decisions that drain your energy.
Step 7: Handle Setbacks Without Giving Up
No one sticks to a budget perfectly. Unexpected expenses, emotional spending, and life events will throw you off track sometimes. The key is how you respond.
When you overspend or miss a goal:
Pause the self-criticism. Beating yourself up will not improve your finances. Treat it as data, not a personal failure.
Ask, “What happened, realistically?” Maybe you underestimated a category, forgot an expense, or used spending to cope with stress.
Adjust your plan. If your grocery category is always blown, increase it and decrease a lower-priority area. A budget must reflect actual life, not fantasy.
Restart immediately. You do not need to wait until next month. You can start a fresh “mini-budget” today for the days remaining.
Over time, you will build financial resilience and confidence by recovering faster from mistakes, not by avoiding them altogether.
Step 8: Celebrate Progress, Not Perfection
Budgeting that works long-term is less about strict rules and more about identity. You are becoming the kind of person who makes intentional decisions with money.
Notice and celebrate small wins:
That first $100 in savings.
Paying off a small debt balance.
Going one week without putting expenses on a credit card.
Choosing to look at your accounts instead of avoiding them.
Each of these is proof that you can change your financial direction. Over months and years, small, consistent actions compound into major transformation.
Your budget is not a prison. It’s a tool to align your money with what matters most to you. Start simple, stay curious, adjust as you go, and let your system evolve with your life. That is how you build budgeting habits that last—and a financial life you can feel proud of and at peace with.