Crushing Debt Strategically: Snowball vs. Avalanche vs. Reality
Debt can feel like a constant weight on your shoulders, stealing your sleep, your future plans, and even your sense of control. You may have heard of the debt snowball method and the debt avalanche method, and maybe you’ve tried to start, stopped, and started again. The truth is, strategies matter—but so does your real life: your emotions, your income swings, and your energy.
This guide will walk you through both approaches, show their strengths and weaknesses, and help you build a plan that respects your actual reality and limits, not a perfect spreadsheet fantasy.
First Step: Get Clear On Your Debt Reality
Before choosing a strategy, you need a brutally honest picture of what you owe. Clarity can be scary, but it’s also incredibly freeing. You can’t win a fight if you don’t know the size and shape of your opponent.
Gather all your debts and write down for each:
- Lender or type of debt (credit card, student loan, car loan, personal loan, etc.)
- Current balance
- Interest rate (APR)
- Minimum monthly payment
- Due date each month
If it feels overwhelming, remind yourself: this is not a judgment on your character. This is simply data to regain financial control. You’re taking leadership of your money instead of letting it control you.
If it helps, sort your debts into two mental categories:
High-stress debts are those that keep you up at night—maybe a debt with family, a collection account, or anything threatening your housing, car, or job.
High-cost debts are those with high interest rates, like many credit cards or payday loans. These grow quickly if not addressed.
Understanding the Debt Snowball Method
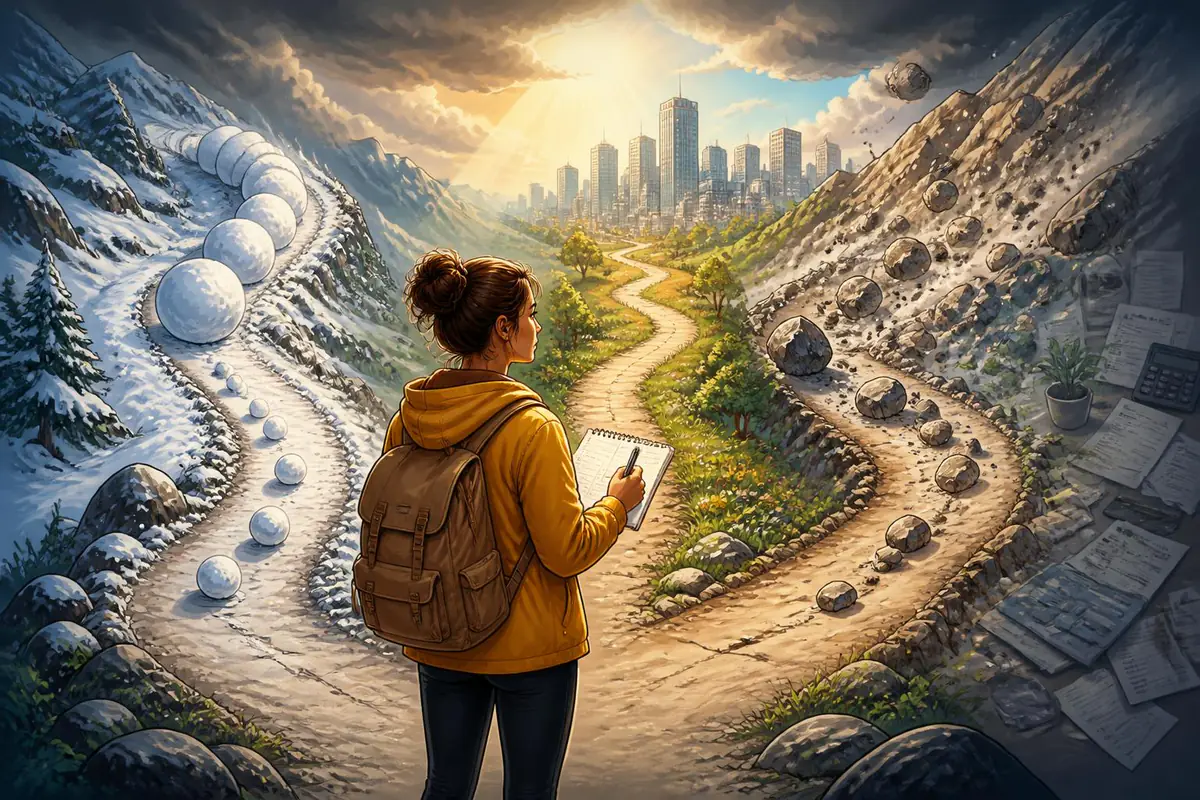
The debt snowball focuses on building motivation and momentum. You pay off debts from the smallest balance to largest balance, regardless of interest rate.
Here’s how it works:
- Pay at least the minimum payment on all debts.
- Choose the debt with the smallest balance and throw every extra dollar at it.
- Once that smallest debt is paid off, roll its entire payment into the next smallest debt.
- Repeat until all debts are gone—your payments “snowball” and grow larger.
The power of snowball is psychological. You get an early win when a small balance disappears. That creates a sense of progress, which fuels your motivation to stick with the plan through tougher stretches.
This method can be especially effective if you’ve struggled with consistency, feel ashamed or discouraged, or need to see quick visible progress to stay engaged. The trade-off is that you might pay more in interest compared to other approaches.
Understanding the Debt Avalanche Method
The debt avalanche focuses on math and minimizing interest. You pay off debts from the highest interest rate to the lowest, regardless of balance size.
Here’s how it works in practice:
- Pay at least the minimum payment on all debts.
- Identify the debt with the highest interest rate and direct all extra money to that one.
- When that debt is gone, redirect its payment to the debt with the next highest rate.
- Continue until every debt is paid off.
The avalanche method usually saves the most money over time because you attack the most expensive debt first. On a spreadsheet, it’s extremely efficient.
However, it can feel emotionally harder. If your highest-interest debt also has a large balance, it may take months or years to eliminate the first account. For some people, this delay in seeing a win can lead to burnout and giving up.
Snowball vs. Avalanche: Side-by-Side Comparison
This comparison can help you see which method aligns more closely with your personality and situation.
| Factor | Debt Snowball | Debt Avalanche |
|---|---|---|
| Main priority | Boost motivation quickly | Minimize total interest cost |
| Order of payoff | Smallest balance first | Highest interest rate first |
| Psychological impact | Frequent early wins | Slower visible progress |
| Financial efficiency | Often pays more interest | Usually pays less interest |
| Best for people who | Need motivation and momentum | Can stay focused without quick wins |
Notice there is no "right" or "wrong" column here. The best method is the one you can follow consistently for as long as it takes to become debt-free.
Bringing Reality Into the Equation
Life rarely follows a perfect repayment plan. Your income might fluctuate, emergencies happen, and your emotional energy changes from month to month. This is where many people get stuck—they pick a method, life hits, and they think they’ve failed.
A better approach is to accept from the start that you’ll need a flexible and resilient strategy. That means:
- Allowing yourself to switch methods if one stops working.
- Adjusting payments during months when money is tighter.
- Temporarily slowing down to handle real emergencies without guilt.
Your plan should serve you, not the other way around. It’s completely valid to start with a snowball to build confidence, then shift to an avalanche once you’re in motion and feel more secure.
Designing a Hybrid Plan That Works For You
You don’t have to be loyal to one method. Many people succeed by blending them into a personalized hybrid strategy. Here are a few ways to do that:
1. Start with snowball, finish with avalanche.
Begin with your two or three smallest balances to build belief that you can actually do this. Then, once you’ve freed up some cash flow and feel stronger, reorder your remaining debts by interest rate and shift into avalanche mode.
2. Respect one emotional debt.
Maybe you have a small but mentally heavy debt—like money owed to a family member or a lingering collection. Consider paying that first, even if the rate is low, to remove the mental burden. After that, go full avalanche or snowball based on what you prefer.
3. Use avalanche as the default, snowball when stuck.
If you hit a wall emotionally, allow yourself to knock out a smaller-balance debt for a quick win, then return to your high-interest target. Think of this as a tool to prevent burnout, not as a failure.
Protecting Yourself While You Pay Off Debt
Another piece of reality: if you throw every spare dollar at debt but have zero buffer, one unexpected car repair or medical bill can send you right back to high-interest credit cards. That’s why it’s often wise to build a small emergency cushion first.
Many people aim for a starter emergency fund of $500–$1,500, depending on income and obligations. It won’t cover everything, but it softens life’s smaller punches so you don’t undo your progress every few months.
As you pay off debt, keep an eye on:
Essential living costs like housing, utilities, food, and transportation.
Basic insurance coverage so that one crisis doesn’t become a financial disaster.
Your mental health and energy, which are just as important as the numbers.
Staying Motivated Over the Long Haul
Debt freedom is usually a marathon, not a sprint. To stay in the race, build habits and systems that support you when motivation fades.
Consider these practical ideas:
- Automate your minimum payments so you don’t miss due dates and fees.
- Set up an automatic extra payment, even if it’s small, to your current target debt.
- Track your total debt balance monthly to see the trend moving down.
- Celebrate milestones: each debt paid off, each $1,000 of total debt gone, or each percent of interest avoided.
Use visual reminders—a chart on the wall, a note on your phone, or a progress bar—so your brain sees that your efforts are working, even when it feels slow.
When to Seek Help Instead of Pushing Alone
Sometimes debt isn’t just about strategy; it’s about sheer volume compared to your income. If you’re constantly behind, using new debt to pay old debt, or facing collection calls and legal threats, individual tactics might not be enough.
In those cases, consider talking to a reputable nonprofit credit counselor or financial advisor who can help you review options like structured repayment plans, negotiating lower interest, or other legal avenues in extreme situations.
Asking for help is not a sign of weakness; it’s a strategic move. You’re the CEO of your financial life—CEOs bring in experts when the situation demands it.
Your Next Action Step—Today
Debt can make you feel powerless, but every plan—snowball, avalanche, or hybrid—starts with a single concrete move. Not a perfect plan, just one step.
Today, choose one of these:
List every debt with balance, rate, and minimum payment. Pick either smallest balance or highest interest as your first target. Or set up one small automatic extra payment, even $20, to your chosen target debt.
The strategy you choose matters less than your decision to keep moving forward consistently. You are not your debt. You’re a person who’s learning, adjusting, and taking back control—one deliberate payment, one realistic plan, and one month at a time.