From Paycheck to Paycheck to Paid Ahead: A 12‑Month Game Plan
Living paycheck to paycheck feels like running on a treadmill: you’re working hard, but you never seem to move forward. Bills, debt, and unexpected expenses keep you stuck, and the idea of being even one month ahead on money can feel impossible.
This 12‑month game plan is designed to help you move from survival mode to stability. You don’t need a huge income or perfect discipline. You need a simple structure, small consistent actions, and the willingness to keep going even when progress feels slow.
Over the next year, you’ll focus on four pillars: clarity, control, protection, and growth. Step by step, you’ll build breathing room into your finances and finally get ahead of your paycheck, instead of chasing it.
Step 1 (Month 1): Get Financially Honest
Before anything can change, you need a clear picture of where you are. This part can feel uncomfortable, but it’s where your power begins. Facing the numbers is not about blame; it’s about building real control over money.
Spend this month gathering:
- All sources of income (after tax)
- All fixed expenses (rent, utilities, insurance)
- All variable expenses (food, fuel, fun, subscriptions)
- All debts (balances, interest rates, minimums)
For 30 days, track every single expense. You can use a notebook, a spreadsheet, or a simple budgeting app. The tool doesn’t matter as much as your consistency. At the end of the month, look at where your money actually went—not where you wish it went.
This clarity will show you your leaks, your patterns, and your opportunities. It turns vague stress into specific, solvable problems.
Step 2 (Month 2): Design a Bare‑Bones Survival Budget
Next, you’ll create two budgets: a realistic one and a backup one. Start with your regular budget: list your income, then your essential expenses, then everything else. Give every dollar a job before the month begins.
Now create your bare‑bones budget. This is the version you would use if things got tight: no extras, no nice‑to‑have spending, just the minimum needed to live and work safely. This might include:
- Rent or mortgage
- Utilities and basic phone plan
- Groceries and necessary transportation
- Minimum debt payments
Your bare‑bones budget is your financial emergency plan. Knowing this number gives you a specific target to cover and makes future decisions much clearer. It also reveals how much room you have to redirect money toward savings and debt in the months ahead.
Step 3 (Months 3–4): Build a Starter Emergency Cushion
If you’re living paycheck to paycheck, almost every setback becomes a crisis. A small emergency fund changes that. It doesn’t need to be huge—just enough to keep an inconvenience from becoming a disaster.
For the next two months, aim to save a starter cushion of $300–$1,000, depending on your situation. To make this realistic:
Look at your tracked spending and choose temporary cuts: a lower data plan, fewer takeout meals, pausing subscriptions, or choosing cheaper entertainment. Then, challenge yourself to find small extra income: selling unused items, freelance tasks, overtime, or side gigs.
Every extra dollar this period goes into a separate savings account labeled something like “Emergency Buffer Only – Hands Off”. You’re buying peace of mind, one deposit at a time. Even a modest cushion can stop the cycle of using credit cards for every surprise.
Step 4 (Months 5–6): Tame Your Debt
Debt is one of the main reasons paychecks disappear so quickly. You may not pay it all off in a year, but you can absolutely start turning the tide. First, list your debts by balance, interest rate, and minimum payment.
Choose a primary strategy:
- Debt snowball: Pay off the smallest balance first for quick wins.
- Debt avalanche: Pay extra toward the highest interest rate to save more money long term.
While keeping all minimum payments current, send any extra cash to your target debt. Even $25–$50 more each month matters over time. If your debt payments are crushing, consider calling creditors to request lower interest, hardship programs, or longer terms. You’re not begging; you’re negotiating.
Your goal by the end of month 6 is not to eliminate every balance, but to have a clear, written plan and at least one debt significantly reduced or gone. That momentum feeds your confidence and creates space in your budget.
Step 5 (Month 7): Smooth Out Irregular Expenses
Unexpected costs are often not truly unexpected—they’re just irregular. Car maintenance, annual fees, school costs, holiday gifts: these hit hard if you haven’t planned for them.
List the non‑monthly expenses you can reasonably predict and estimate their yearly cost. Divide each by 12 to find the monthly amount you need to set aside. Even if you can’t fully fund everything yet, start with the biggest troublemakers, such as car repairs or medical co‑pays.
| Expense | Yearly Cost | Monthly Amount |
|---|---|---|
| Car maintenance | $600 | $50 |
| Holiday gifts | $480 | $40 |
| Medical co‑pays | $360 | $30 |
If your bank offers multiple savings “buckets” or sub‑accounts, label them for each category. Watching those amounts grow reminds you that you are planning problems before they appear, not just reacting when they do.
Step 6 (Months 8–9): Build a One‑Month Buffer
Now you start breaking the paycheck‑to‑paycheck cycle directly. The goal of these two months is to begin building a one‑month buffer: money that covers next month’s expenses before the month starts.
Here’s the idea: instead of using this month’s paycheck to pay this month’s bills, you gradually shift so that this month’s income pays next month’s bills. Even getting one week ahead is progress. Aim to accumulate at least one week of expenses, then two, and keep building.
During these months, keep your lifestyle as steady as possible. Any unexpected extra income, tax refunds, gifts, or overtime should go into your buffer fund. This isn’t about deprivation forever; it’s about a short‑term push to create long‑term breathing room.
Step 7 (Month 10): Automate and Simplify
By now, you have a clearer budget, some emergency savings, a debt plan, and the beginnings of a buffer. To make sure you don’t slide backward, you’ll automate as much as possible.
Set up automatic transfers and payments right after each paycheck hits:
First, move money to savings (emergency, buffer, and sinking funds). Then, schedule automatic bill payments for fixed expenses. Whatever remains is your flexible spending for the pay period.
Automation helps protect you from forgetfulness, temptation, and decision fatigue. You’re using systems, not just willpower, to stay on track. This is how good habits become effortless over time.
Step 8 (Months 11–12): Strengthen, Review, and Plan Ahead
The final two months of your 12‑month game plan are about solidifying your progress and looking forward. Start by reviewing your year: What changed? What still feels tight? Where did you surprise yourself?
Revisit your goals. Do you want to fully fund a one‑month buffer? Push your emergency fund higher? Attack a specific debt? Choose 1–3 priorities for the next year and adjust your budget accordingly.
Then, strengthen your foundation:
- Increase automatic savings by a small percentage if possible.
- Update your bare‑bones budget if income or expenses have changed.
- Refine your debt strategy based on new balances.
By month 12, you may not be rich, but you are no longer the same person who started. You have systems, awareness, and a growing sense of financial stability. You’re building a future on purpose, not by accident.
Mindset Shifts That Make This Plan Work
Practical strategies only work when they’re supported by healthier beliefs about money. As you move through the year, keep these mindset shifts in view.
First, progress matters more than perfection. Some months won’t go as planned. That doesn’t erase your work. Adjust, learn, and restart the plan where you are. Consistency over time beats intensity for a week.
Second, every dollar has power. Even small amounts redirected toward savings or debt change your trajectory. Don’t wait for a better job or a windfall to start. You are practicing the skills now that you’ll need when your income grows.
Third, you are not your financial past. Maybe you’ve made choices you regret. Maybe life hit you with expenses you never anticipated. Either way, your worth is not measured by your bank balance. This 12‑month plan is not punishment; it’s an act of self‑respect.
From Surviving to Paid Ahead
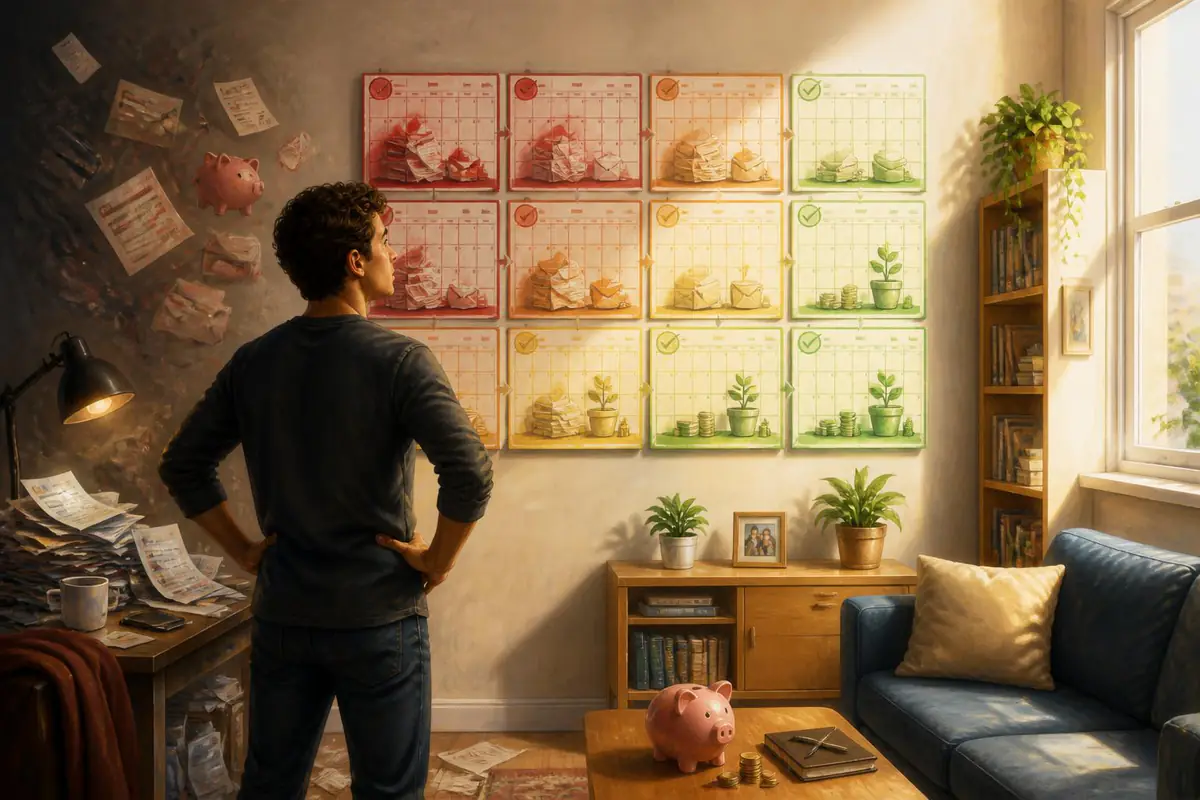
Imagine this: Your bills for next month are ready to be paid before the month even begins. An unexpected car repair is a hassle, not a crisis. Debt is shrinking, not growing. You check your accounts with curiosity instead of dread.
This is what it means to move from paycheck to paycheck to being paid ahead. It doesn’t happen overnight, but it does happen step by step, choice by choice, month by month. Your future self is waiting for the version of you who starts today.
You don’t need perfect conditions to begin. You need a simple plan, a bit of courage, and the decision to treat your money as a tool for building the life you want. Over the next 12 months, you can create that shift—and finally step off the financial treadmill for good.