Inflation, Recession, and Rates: Economic Concepts You Really Need to Know
Economic news can sound like a different language. One week, you hear about inflation hitting new highs. The next, everyone is worried about a recession. Then central banks raise or cut interest rates, and markets suddenly react. It can feel distant and abstract, yet these forces directly shape your rent, your job security, and the price of your groceries.
Understanding these ideas is not just for economists or investors. It’s for anyone who wants to protect their money, make better decisions, and feel more in control of their financial future. When you learn how inflation, recession, and interest rates work together, you can move from reacting in fear to planning with confidence.
What Inflation Really Means for Your Daily Life
Inflation is simply the general increase in prices over time. When inflation rises, the same amount of money buys less than it used to. You notice it when your weekly groceries cost more, your rent creeps up, or services like haircuts and repairs get pricier.
Economists usually measure inflation using price indexes, which track how the cost of a typical basket of goods and services changes. For you, the important part is not the exact formula but the impact: inflation quietly erodes your money. If your wages or income grow slower than prices, your real purchasing power falls.
Some inflation is normal and even healthy. Central banks in many countries aim for a low and stable rate, often around 2%. That kind of inflation signals that the economy is growing and people are spending. The trouble starts when inflation becomes very high or unpredictable. Then businesses struggle to plan, households feel stressed, and people may cut back sharply on spending.
How Recessions Happen and Why They Matter
A recession is a significant decline in economic activity that lasts more than a few months. In practice, it shows up as falling output, rising unemployment, and lower business and consumer confidence. Wages stagnate or fall, job searches take longer, and companies may delay investments.
Recessions often follow periods of rapid growth or major disruptions, like financial crises or global shocks. When households and businesses become cautious, they spend and invest less. That reduced demand can lead to layoffs, which in turn cause further cuts in spending, creating a negative cycle.
However, recessions are also part of the economic cycle. They are painful, but they often push companies and governments to correct imbalances, rethink priorities, and improve efficiency. For individuals, understanding that recessions are cyclical can help you prepare rather than panic.
The Role of Interest Rates: The Economy’s Volume Knob
Interest rates are the price of borrowing money and the reward for saving it. Central banks set a key short-term interest rate that influences many others: mortgage rates, car loans, credit cards, and even the interest you earn on savings accounts.
When inflation is high, central banks typically raise rates. Higher rates make borrowing more expensive and saving more attractive. As people and businesses slow their borrowing and spending, demand cools, which can help bring inflation down.
When the economy is weak and unemployment is high, central banks often cut rates. Lower rates make loans cheaper and can encourage business investment and household spending. The goal is to support growth and reduce the risk of a prolonged recession.
Think of interest rates as the economy’s volume knob. Turning it up or down doesn’t change everything instantly, but over months and years it shapes the rhythm of growth, prices, jobs, and investment opportunities.
How Inflation, Recession, and Rates Interact
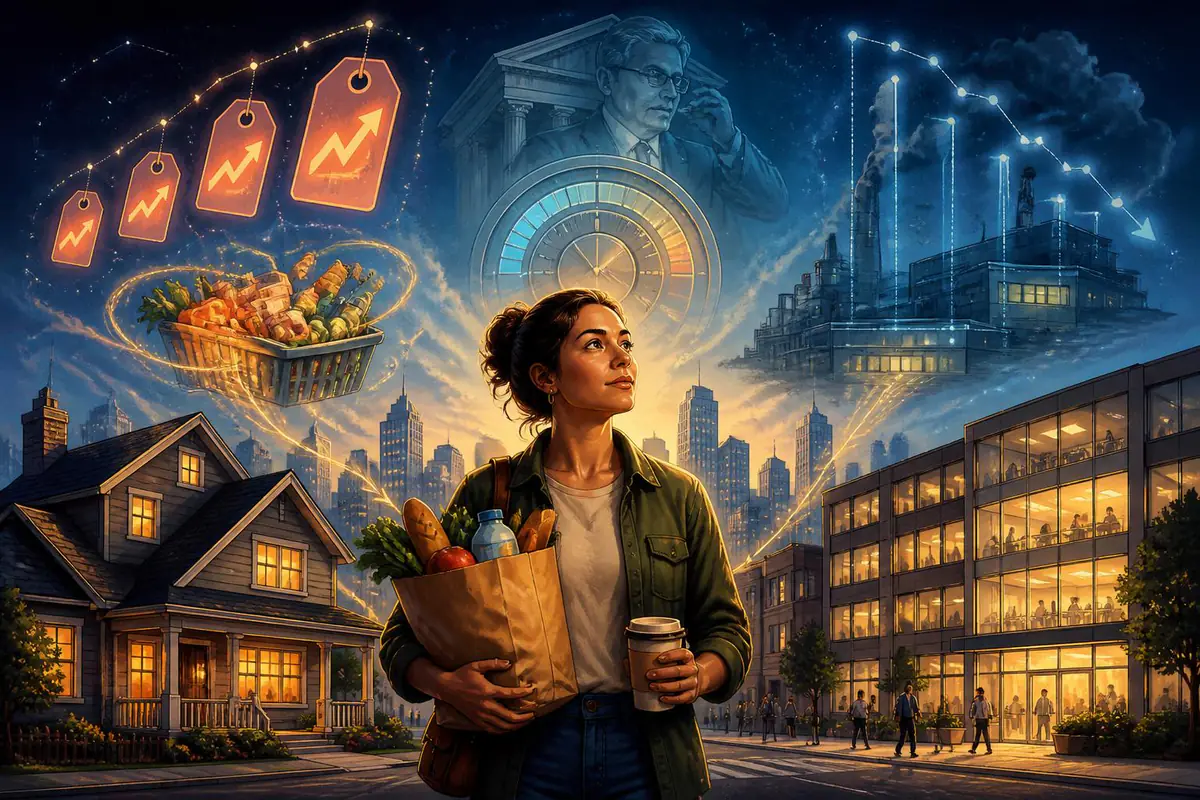
These three concepts form a powerful triangle. Each affects the others, and together they drive much of what you experience in the economy.
| Situation | Inflation | Economy | Typical Rate Policy |
|---|---|---|---|
| Overheating economy | Rising quickly | Strong growth, low joblessness | Raise interest rates |
| Recession risk | Falling or low | Weak growth, higher unemployment | Cut interest rates |
| Stagflation risk | High and sticky | Weak growth, job pressures | Challenging: often still tighter |
In an overheating economy, strong demand pushes prices up. Central banks respond with higher rates to cool things down, which can eventually slow growth and bring inflation back to target.
In a downturn, spending and investment drop, unemployment rises, and inflation often eases. Lowering rates is one tool to support a recovery. But if inflation remains high even while growth is weak, policymakers face a tough balance: raising rates to fight inflation can deepen the slowdown, while cutting rates risks letting prices spiral.
Practical Strategies to Protect Yourself from Inflation
You cannot control inflation, but you can adapt. Instead of ignoring it or simply worrying, use it as a signal to review your financial habits and plans.
- Track your real cost of living: Compare your income growth to your actual expenses over the last 12–24 months. If prices are rising faster than your pay, you need a plan.
- Build an emergency buffer: Aim for a cash reserve that covers several months of essential expenses. In high inflation, try to keep this money in accounts that at least earn some interest.
- Limit long-term fixed low income: If possible, avoid relying heavily on income that doesn’t adjust with inflation, such as very low fixed rents from a small property or long-term contracts without indexation.
Consider how your savings are positioned. Holding everything in cash when inflation is high guarantees that your purchasing power shrinks over time. That doesn’t mean taking reckless risks, but it does mean exploring options where returns can potentially outpace inflation, consistent with your risk tolerance.
Preparing for Recessions Before They Hit
By the time the news declares a recession, many companies and households have already felt it. Preparing in advance can reduce stress and give you more flexibility when conditions worsen.
Focus on strengthening your personal balance sheet: lowering debt, increasing savings, and stabilizing income sources where possible. During good times, it’s tempting to assume growth will continue indefinitely. That’s exactly when it’s most important to prepare.
Ask yourself:
- If I lost my main source of income, how long could I cover essentials without borrowing?
- Do I rely heavily on one employer, one client, or one industry that might be vulnerable in a downturn?
- Are there skills I could develop now to remain valuable in a cooler job market?
You can’t fully remove recession risk, but you can make it far less dangerous. A solid emergency fund, flexible skills, and controlled debt turn a recession from a personal crisis into a tough period you can navigate.
Making Smarter Decisions About Debt and Interest Rates
Interest rates directly affect your loans: mortgages, student debt, car finance, and credit cards. In a rising-rate environment, variable-rate debt becomes more expensive. Monthly payments can increase, sometimes sharply, which puts pressure on your budget.
Use this knowledge to make choices that protect you:
- Prioritize high-interest debt: Credit card balances and other expensive loans can become unbearable when rates rise. Paying these down quickly is often one of the best risk-free "investments" you can make.
- Consider fixed versus variable: A fixed-rate mortgage or loan gives you predictable payments, which can be valuable when rates are volatile. A variable rate may be cheaper at first but could rise later.
- Match debt to the life of the asset: Long-term assets like homes can justify long-term debt. Short-lived purchases funded with long-term borrowing can lock you into payments long after the benefit has faded.
On the saving side, higher interest rates can be helpful. Shop around for better returns on savings accounts, certificates of deposit, or other low-risk vehicles. Even modestly higher interest can help offset some inflation, especially on cash you need to keep safe.
Turning Economic Knowledge into Personal Power
Inflation, recession, and interest rates may sound abstract, but they shape your everyday life. When you understand them, you are less likely to be surprised, misled, or paralyzed by fear. Instead, you can respond thoughtfully.
Use high inflation as a prompt to review your budget, revisit your savings strategy, and seek income that can grow over time. Use good economic times to prepare for the next downturn by strengthening your financial foundation, developing skills, and avoiding unnecessary debt. Watch interest rate trends so you can make smarter decisions about borrowing and saving.
You don’t need a degree in economics to navigate these forces. You need curiosity, a willingness to learn, and the discipline to act on what you learn. Step by step, you can transform confusing headlines into clear signals — and turn those signals into better, more resilient choices for your financial future.