The Psychology of Spending: Why Your Brain Sabotages Your Savings
Your struggle to save money is not just about math. It is deeply about how your brain interprets money, rewards, and future risks. Even if you know you should save, you may still feel pulled toward spending, upgrades, and instant comforts.
Understanding the psychology behind your spending habits does not just explain your behavior; it gives you practical levers you can control. When you know why your brain resists saving, you can design systems that work with your mind, not against it.
Why Your Brain Loves Now and Ignores Later
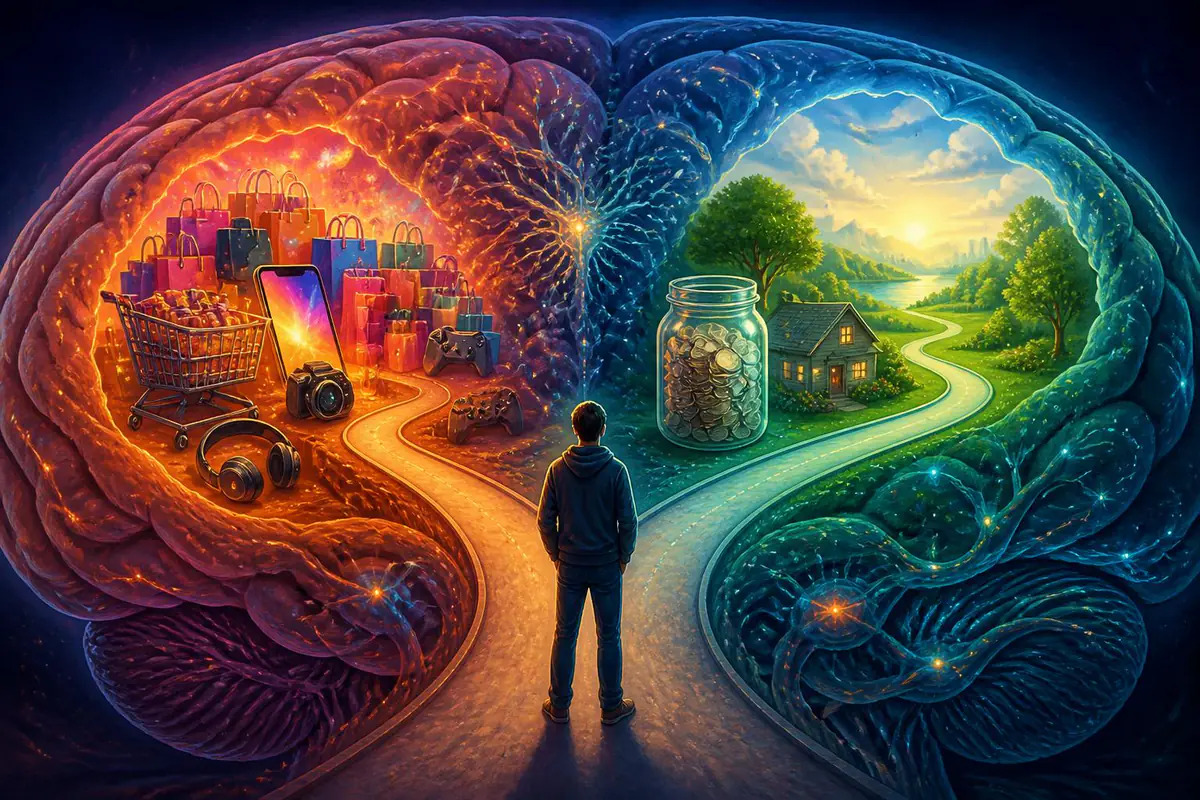
The biggest enemy of saving is not a lack of willpower. It is a normal brain bias called present bias and instant gratification. Your brain is wired to prioritize immediate rewards over distant ones.
Spending money gives a quick hit of dopamine. Buying coffee, scrolling shopping apps, or upgrading your phone all provide an immediate emotional reward. Saving money, on the other hand, feels vague and far away: a retirement fund, emergency cushion, or future home. Your brain struggles to get excited about a reward that may be years or decades away.
This is why you can sincerely want to save and still feel a strong pull to spend. Your emotional brain and your rational brain are having a quiet argument, and the emotional brain often wins in the moment.
The Hidden Traps That Push You to Spend
Several well-known psychological patterns quietly nudge you to spend more than you intend. Once you recognize them, they become much easier to resist.
1. The pain of paying
Paying with cash feels painful because you physically see money leaving your hands. Digital payments, automatic renewals, and contactless taps reduce that pain. When paying does not feel painful, you naturally spend more without noticing.
2. Mental accounting mistakes
Instead of treating all money equally, your brain divides it into “mental accounts.” For example, you might spend a tax refund on luxuries because it feels like “extra or free money”, even though it could have gone to savings or debt. You may also treat a work bonus differently from your regular salary, even though both are simply income.
3. Lifestyle creep and comparison
As income rises, spending quietly rises with it. You get used to nicer restaurants, more subscriptions, and better gadgets. Add social media comparison to the mix and your brain starts to treat certain comforts as “normal” instead of “extra.” This creeping normal of spending makes saving feel like a sacrifice instead of progress.
4. The sale and discount illusion
“50% off” can feel like you are making money, not spending it. Your brain focuses on the discount instead of the actual cost. You may buy things you did not need, just because it felt like a smart decision. In reality, you are trading long-term security for a short-term thrill of “winning a deal.”
Emotions: The Quiet Drivers Behind Your Purchases
Money is rarely just about numbers. It is tangled up with identity, fear, status, and even love. When you understand your emotional patterns, you can begin to change them.
Stress and emotional spending is one of the most common patterns. After a hard day, buying something small can feel like relief or a reward. You are not buying the item; you are buying a mood shift. The problem is that the relief is temporary, but the financial impact is permanent.
There is also the issue of identity. Your purchases often reflect who you believe you are, or who you want to be: a generous friend, a successful professional, a fun parent, or a person with great taste. This can lead to spending that quietly says, “This is who I am now”, even when your bank account disagrees.
Fear and shame play roles, too. If you feel ashamed of past money mistakes, you may avoid looking at your finances. That avoidance keeps you from planning and saving, which in turn creates more anxiety and more avoidance. It becomes a painful loop.
How Marketers Use Your Brain Against Your Savings
Modern marketing is built on behavioral psychology. Companies design experiences to reduce the “pain of paying” and raise the excitement of buying. Understanding these tactics helps you protect your savings.
- Infinite scroll and one-click checkout make it effortless to move from desire to purchase.
- Limited-time offers trigger scarcity, pushing you to buy quickly before you can reflect.
- Personalized ads mirror your tastes and target your existing desires, reducing resistance.
- Subscription models hide costs in small monthly amounts that seem harmless but add up.
None of this means you should never spend. It means you should remember: when you shop, you are not just facing products. You are facing sophisticated systems built to encourage spending. Your best defense is awareness and pre-decided rules.
Practical Ways to Outsmart Your Spending Instincts
You will not change your brain’s wiring, but you can change your environment and habits. The key is to make saving easy and automatic, and spending slightly harder and more deliberate.
1. Pay your future self first
Set up automatic transfers to savings the same day you receive income. Treat this like a non-negotiable bill, not an optional leftover. When saving happens before you see the money, your brain adjusts to a lower “normal” spending level.
If possible, split it: emergency fund, long-term savings, and specific goals. Even small amounts give your brain a sense of progress and control.
2. Use friction wisely
Make saving easy and spending inconvenient. For example:
- Delete stored card details from shopping sites so checkout requires effort.
- Remove shopping apps from your phone and use them only on a computer.
- Enable a 24-hour or 48-hour rule for non-essential purchases.
These small obstacles give your rational brain time to wake up and ask, “Do I truly need this?”
3. Reframe saving as a reward
Your brain needs emotional rewards, not just logic. Turn saving into something that feels satisfying now, not just later.
Try visual progress trackers, such as a chart on your wall or a digital goal bar. Each contribution becomes a mini victory. You might tell yourself, “I am buying future freedom today” whenever you move money into savings. Over time, your identity shifts from “someone who struggles with money” to “someone who protects their future.”
4. Name your accounts with meaning
Instead of a generic “Savings” account, rename accounts with emotionally meaningful labels:
| Generic Label | Emotional Label |
|---|---|
| Savings | Safety Net for My Family |
| Emergency Fund | Stress-Free Crises Fund |
| Retirement | Freedom to Choose My Life |
| Travel Fund | Memories and Adventures Account |
These names help your brain see saving as something deeply connected to your values, not just delayed consumption.
5. Prepare scripts for emotional spending moments
Decisions made when you are tired, stressed, or upset are rarely your best. Create simple phrases you can use in those moments, such as:
- “If I still want this in 48 hours, I can buy it.”
- “Is this solving my problem, or just numbing my feelings?”
- “What would my future self thank me for?”
Scripts reduce the mental energy needed to resist temptation and reinforce the identity of a mindful spender.
Turning Awareness Into Lasting Change
Knowing the psychology is powerful, but change happens through repetition and design, not single moments of insight. Start small and focus on building confidence, not perfection.
Pick one or two strategies—automatic savings, a 24-hour rule, or deleting shopping apps—and commit to testing them for a month. Observe how your feelings around money shift. Each small success tells your brain a new story: you are capable, intentional, and learning.
Your brain may always be tempted by instant gratification, but it can also learn to love security, freedom, and stability. Over time, saving will feel less like deprivation and more like an act of care for your future self. That is when your brain stops sabotaging and starts supporting your financial life.
You do not need a different brain to save more. You need to understand the one you already have—and build habits that gently guide it toward the future you want.