Understanding Interest: The Difference Between Good Debt and Bad Debt
Debt itself is not automatically good or bad. What truly matters is how the debt works in your life, how much it costs you, and whether it moves you closer to or further from your financial goals. To understand this, you must first understand interest: how it’s calculated, how it grows, and why some interest can be a powerful tool while other interest quietly destroys your wealth.
When you clearly see the difference between good debt and bad debt, you can stop feeling confused or guilty about money you owe and instead make calm, confident decisions. You’ll know when to borrow, when to avoid it, and which debts to attack first.
What Is Interest, Really?
Interest is the price you pay to use someone else’s money. When you borrow, the lender charges you interest; when you invest or save, you may earn interest. Understanding this price is essential for judging whether a debt is helpful or harmful.
There are two main ways interest can be calculated: simple interest and compound interest. Simple interest is charged only on the original amount you borrowed. Compound interest is charged on the original amount plus any interest that has already been added. Over time, compound interest can become a powerful wealth builder or a dangerous trap if you are on the paying side.
For example, a high-interest credit card that compounds daily can make a manageable balance explode into a serious burden, while a retirement account earning compound interest can grow your savings dramatically over many years.
Good Debt vs Bad Debt: The Core Difference
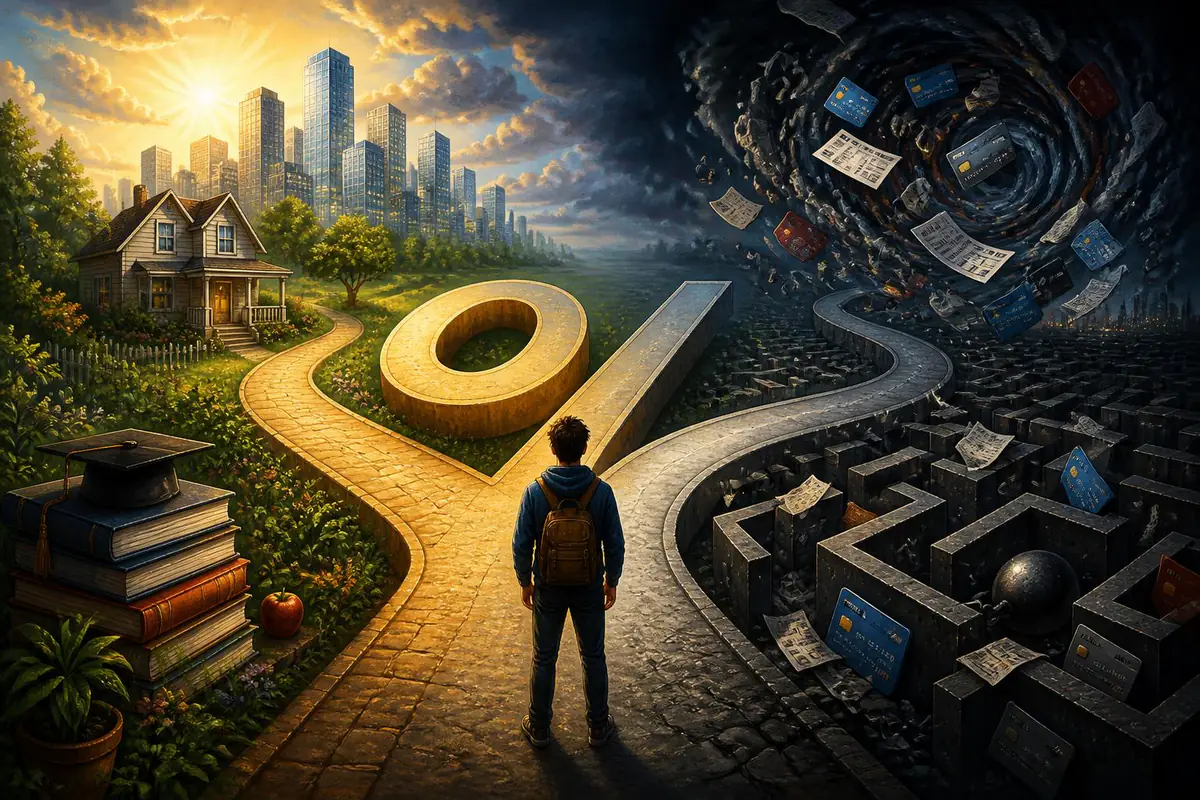
Good debt is borrowing that is likely to make you richer or improve your long-term well-being. Bad debt is borrowing that is likely to make you poorer without meaningful long-term benefit.
The core questions to ask are:
- Does this debt help me build lasting financial value?
- Is the interest rate reasonable compared to potential benefits?
- Do I have a realistic plan to repay it on time?
If you can answer “yes” to these questions, the debt may be good. If the honest answer is “no,” or if the main purpose is to cover everyday spending you cannot afford, you are likely looking at bad debt.
Examples of Good Debt
Good debt is not perfect or risk-free, but it is debt that has a strong chance of improving your financial position. It usually finances an asset or skill that can increase your income or reduce your costs over time.
Common examples include:
- Reasonable student loans that fund education or training which consistently increases earning potential in your field.
- A manageable mortgage on a home you can afford, in a stable area, where your monthly payment fits easily within your budget.
- Business loans with a plan that allow you to grow a profitable business with clear projections and a careful repayment strategy.
These types of debts can be considered “good” only if the costs are under control. A small student loan for an in-demand degree is different from a massive loan for a field with limited job prospects. A modest mortgage is very different from taking on a home that stretches your budget to the breaking point.
Good debt usually has relatively lower interest rates, clear terms, and connects to specific long-term goals. The interest is the cost of investing in your future, not a fee for short-term comfort.
Examples of Bad Debt
Bad debt typically funds consumption, not investment. It often comes with high interest rates and no realistic expectation that the purchase will increase your earnings or long-term financial stability.
Examples of bad debt include:
- High-interest credit card balances due to lifestyle spending, impulse purchases, or vacations.
- Rent-to-own agreements and store financing with hidden fees and extremely high effective interest.
- Personal loans used to maintain a lifestyle already beyond your means, instead of adjusting spending.
In these situations, you are borrowing against your future income to pay for things that are quickly consumed or depreciate in value. The interest you pay buys the illusion of comfort today but quietly drains your financial strength tomorrow.
Bad debt often feels normal because many people live this way, but normal is not the same as healthy. The more of this interest you pay, the harder it becomes to save, invest, and move toward real financial freedom.
How Interest Turns Good Debt into Bad Debt
Even a potentially good type of debt can become harmful if the interest rate or loan size is too high. A mortgage that consumes most of your income can keep you stressed and fragile. Student loans with heavy balances and high rates can delay major life decisions for years.
To see this clearly, consider how different interest rates change your total cost. A slightly higher rate over many years can mean paying tens of thousands more. This is where understanding the math truly empowers you.
| Debt Type | Interest Rate | Likely Category | Key Risk |
|---|---|---|---|
| Student loan for a strong career field | 4% fixed | Often good debt | Borrowing more than needed |
| Mortgage within safe budget limits | 6% fixed | Often good debt | Job loss or income drop |
| Credit card for everyday spending | 22% variable | Usually bad debt | Compounding interest spiral |
| Personal loan for a vacation | 15% fixed | Usually bad debt | No lasting financial benefit |
This table shows that the same type of borrowing can shift category depending on how it is used. The combination of purpose, rate, and repayment plan determines whether the debt will help you or harm you.
How to Decide: Is This Debt Worth It?
Before taking on any new debt, pause and ask yourself a few powerful questions. These questions help you see beyond the emotion of the moment and evaluate the true cost.
Ask yourself:
1. Will this debt increase my income, skills, or long-term security in a realistic, measurable way?
2. Can I clearly afford the monthly payment without stretching my budget?
3. What is the total interest I will pay over the life of the loan?
4. Do I have a backup plan if my income drops or expenses rise?
If you cannot answer these questions with confidence, consider delaying the decision. Often, the simple act of waiting reveals whether this is a true priority or just a reaction to pressure or desire.
Practical Steps to Turn Your Debt Situation Around
You are not defined by past borrowing decisions. No matter where you are starting, you can use interest to your advantage going forward. That means reducing bad debt, optimizing good debt, and building savings that earn interest instead of paying it.
Here is a practical path you can follow, starting from wherever you are today:
- List every debt you have: include the balance, interest rate, minimum payment, and due date.
- Sort by interest rate: high-interest debts (like credit cards) usually become top priority.
- Choose a payoff strategy: either the debt avalanche (highest rate first) or the debt snowball (smallest balance first for motivation).
- Negotiate where possible: call lenders to request lower interest, longer terms, or hardship options.
- Redirect freed-up money: after you pay off one debt, move that payment to the next one.
As you work through this, protect yourself from sliding back into bad debt. Build a small emergency fund so unexpected expenses do not always go on a high-interest card. Keep your lifestyle slightly below your income so there is room to save, invest, and breathe.
Over time, your relationship with interest will change. Instead of being the person who pays high interest every month, you become the person who earns interest on savings and investments. This shift is one of the most powerful steps toward long-term financial independence.
Redefining Your Relationship with Debt
Understanding the difference between good debt and bad debt is not about judging yourself; it is about gaining clarity. Good debt is a carefully chosen tool. Bad debt is an unnoticed drain. Interest is the engine behind both, and learning how it works gives you control.
When you borrow with intention, calculation, and a clear plan, debt can help you build a career, a home, or a business. When you borrow from habit, emotion, or pressure, debt can steal your options and your peace of mind.
You have the ability to change this story. By recognizing the role of interest, questioning each new debt, and creating a strategy to reduce harmful balances, you move steadily toward a life where debt serves you instead of ruling you. The goal is not to fear all borrowing, but to use it wisely, in alignment with your deepest financial goals and the future you truly want.