Warning Signs of Predatory Lending and How to Avoid It
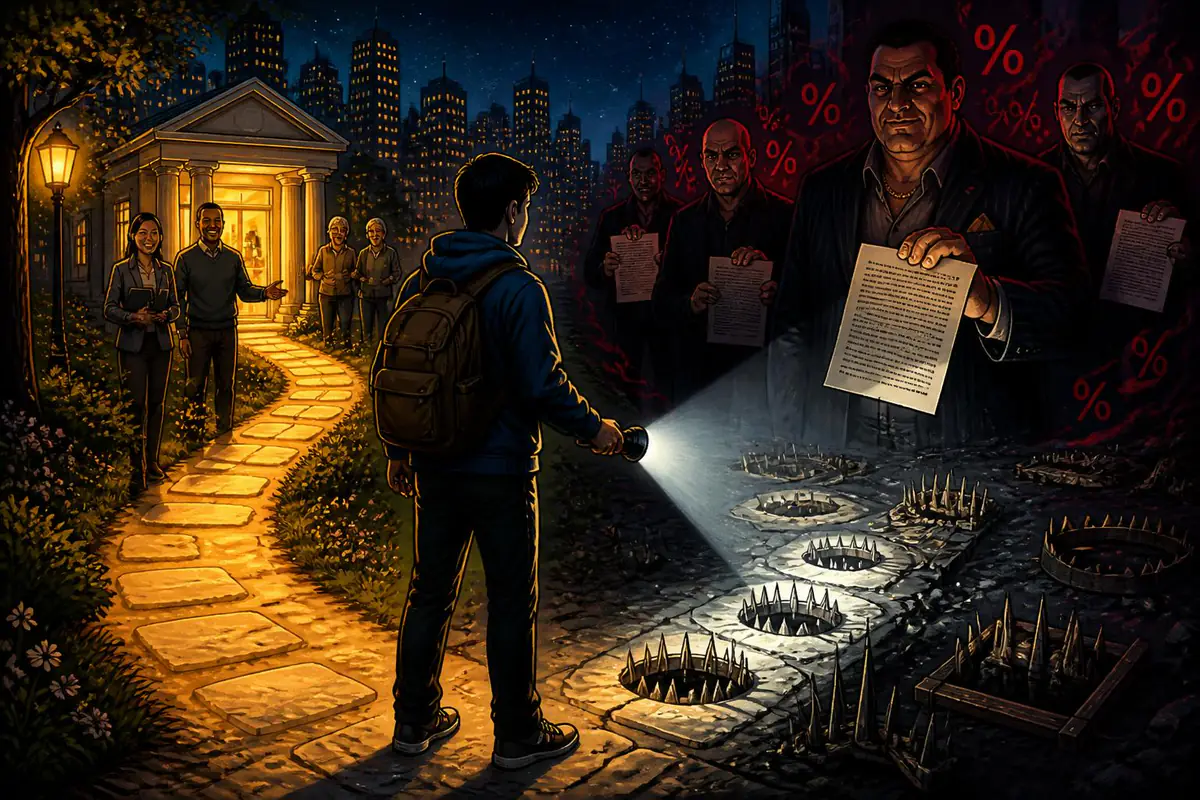
Predatory lending hides behind friendly smiles, urgent promises, and paperwork that seems impossible to understand. It targets people who are stressed, rushed, or unsure of their financial options. The more pressure you feel, the easier it becomes for a dishonest lender to take advantage of you.
Recognizing the warning signs of predatory lending can protect your money, your credit, and your peace of mind. You do not need to be a financial expert to stay safe. You just need awareness, a few simple tools, and the confidence to slow things down and ask questions.
What Is Predatory Lending?
Predatory lending happens when a lender uses unfair, abusive, or deceptive practices to trap borrowers in debt. These lenders often target people who feel desperate: those with low credit scores, limited savings, or urgent financial needs.
Instead of helping you succeed, a predatory lender designs the loan so that the lender always wins and the borrower struggles. The terms may be legal on paper, but they are deeply unfair in practice, often leading to late fees, repossessions, or even foreclosure.
Common Types of Predatory Loans
Predatory behavior can appear in many types of loans. Knowing where it commonly shows up helps you stay alert whenever you borrow.
- Payday loans: Short-term loans with extremely high fees or interest, usually due on your next paycheck. They are marketed as quick fixes but often become debt traps.
- Car title loans: Loans that use your car as collateral. If you cannot repay, you risk losing your vehicle even if you only borrowed a small amount.
- High-fee personal loans: Personal or installment loans with hidden charges, unnecessary add-ons, and confusing terms.
- Unfair mortgages: Home loans with balloon payments, adjustable rates that skyrocket, or terms you do not fully understand.
- Subprime credit offers: Credit cards or financing programs targeting people with poor credit, often loaded with fees and penalties.
Not every payday lender or subprime loan is automatically predatory, but the risk is higher in these categories. The key issue is whether the loan is structured to help you succeed financially or to profit from your struggle.
Major Warning Signs of Predatory Lending
Unfair lenders use similar tricks again and again. When you spot the following warning signs, slow down or walk away.
1. Pressure to Sign Immediately
Predatory lenders do not want you to think too long. They might push you with phrases like, “This offer expires today,” or “If you leave, the deal is gone.”
When someone pressures you to sign fast, ask yourself why. A fair lender will encourage careful reading and questions. If you feel rushed, that is a strong signal to step back and get advice.
2. Terms That Feel Too Confusing
If you cannot explain your loan in simple language, you probably should not sign it yet. Predatory lenders often use:
- Complex fee structures that are difficult to follow
- Interest that can change dramatically over time
- Extra products, like insurance, bundled without clear explanation
Ask the lender to explain everything in plain words: total cost, monthly payment, length of the loan, and what happens if you pay late. If they cannot or will not provide clear answers, the loan is not safe.
3. Extremely High Interest and Fees
Some loans advertise a low monthly payment but hide enormous fees and interest. For example, a payday loan might show a fee of $15 per $100 borrowed, which does not sound terrible. But over a year, that can become an annual percentage rate shockingly high, sometimes more than 300%.
Always look for the APR (Annual Percentage Rate). This number shows the real yearly cost of borrowing, including interest and most fees. When the APR is far higher than typical bank or credit union loans, be extremely cautious.
4. No Real Check of Your Ability to Repay
Responsible lenders want proof you can repay a loan without serious hardship. They may ask for pay stubs, bank statements, or other financial details.
Predatory lenders often skip this step. They may say, “No credit check required,” or, “Everyone is approved.” While this sounds welcoming, it can mean the lender does not care if the loan will destroy your budget. Instead, they rely on late fees, rollover fees, or seizing collateral.
5. Collateral That Costs More Than the Loan
Using your home or car to secure a small loan is risky. Some lenders encourage people to borrow relatively small amounts while putting up very large collateral.
For example, using your car title for a $1,000 loan may place your entire vehicle at risk. If the lender seems eager for you to risk major assets unnecessarily, this is a serious red flag.
6. Promises to Ignore or Fix Bad Credit
Lenders who advertise, “We don’t care about credit” or “We can erase bad credit,” may be trying to hook people who feel they have no other options.
In reality, no lender can magically erase your history. They can only report new information going forward. If someone promises to clean your credit quickly for a fee or as a loan condition, walk away.
7. Fees for Paying Off the Loan Early
A fair loan should allow you to pay off your debt as soon as you are able. Some predatory lenders charge extra fees if you pay early, known as prepayment penalties.
This keeps you locked into a long, expensive loan. If early payoff triggers a big penalty, question whether the loan is truly in your best interest.
A Simple Table to Compare Offers
When comparing loans, organize the basics. This helps you clearly see which offer is safest and most affordable.
| Loan Feature | Offer A | Offer B |
|---|---|---|
| Loan Amount | $ | $ |
| APR (Annual Percentage Rate) | % | % |
| Loan Term (months/years) | ||
| Monthly Payment | $ | $ |
| Total Repayment Cost | $ | $ |
| Prepayment Penalty? | Yes/No | Yes/No |
Filling in this table for each offer exposes overpriced loans and misleading “low payment” deals. It puts you back in control.
How to Protect Yourself Before You Borrow
Awareness is powerful, but you also need practical steps. Here are actions you can take to avoid predatory lending and choose safer options.
- Slow down the process: Never sign a loan on the same day you first hear about it. Take the documents home, review them calmly, and ask someone you trust for help.
- Shop around: Get quotes from banks, credit unions, and reputable online lenders. Seeing multiple offers makes it easier to spot unfair ones.
- Read every page: Pay attention to interest rate, fees, total cost, and what happens if you are late. If any part is unclear, insist on explanations in plain language.
- Check the lender’s reputation: Look for complaints, legal actions, or patterns of negative reviews that mention hidden fees or aggressive collection tactics.
Taking even one of these steps reduces the chance that you will be trapped in a harmful agreement. Combining them gives you a strong layer of protection.
Healthier Alternatives to Risky Loans
If you feel stuck, remember that predatory loans are not your only option. Consider alternatives that are often safer and more affordable, such as:
Talking with your utility company, landlord, or creditors about payment plans. Many will work with you if you explain your situation early, especially before you miss payments.
Exploring personal loans from banks or credit unions, even if you think your credit is weak. Some have special programs for people rebuilding credit.
Seeking help from nonprofit credit counselors, who can review your debts, create a plan, and sometimes negotiate with creditors.
These options may take a bit more time and effort, but they build a foundation for long-term financial stability instead of feeding a cycle of crisis borrowing.
Trusting Your Instincts and Taking Back Control
When you feel tired, worried, or desperate, it is easy to believe that any solution is better than no solution. Predatory lenders rely on this feeling. They appear when you are vulnerable, promising fast relief without mentioning long-term pain.
Yet you have more power than it may seem. You can ask questions, compare offers, walk away, and seek guidance. You can insist on terms that are fair, clear, and sustainable. Whenever a loan offer makes you uneasy, that discomfort is valuable information. Your instincts are often your first line of defense.
Protecting yourself from predatory lending is not just about money. It is about defending your future, your options, and your sense of security. With awareness of the warning signs and a willingness to pause before signing, you can avoid the traps and choose paths that support your goals instead of undermining them.
Every time you say “no” to an unfair loan, you say “yes” to your own financial strength. That decision, repeated again and again, is how you build a life shaped by intention, not pressure.