Behavioral Biases That Sabotage Your Investment Returns
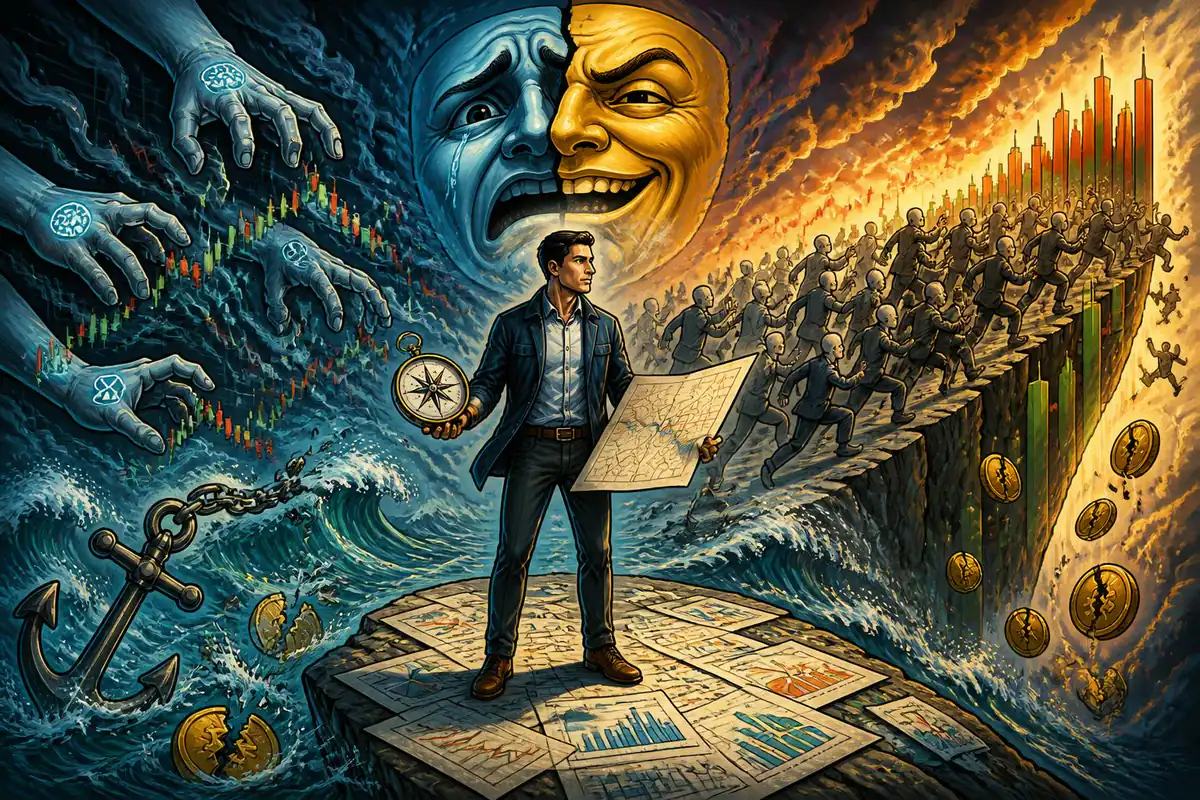
Most investors do not underperform the market because they lack information or access to tools. They underperform because of their own minds. Hidden in everyday decisions are powerful psychological shortcuts and emotions that feel natural, yet quietly eat away at long‑term returns.
Understanding these behavioral biases is the first step. Building practical defenses against them is the second. When you do both, you transform investing from a stressful guessing game into a disciplined process you can trust through bull and bear markets.
Why Smart People Make Costly Investing Mistakes
Intelligence does not protect you from behavioral biases. In fact, confident, analytical investors are often more vulnerable because they believe they are immune. Biases work at an emotional level, often below awareness, shaping what we notice, how we interpret news, and when we act.
Money decisions trigger fear, greed, pride, and anxiety. These emotions evolved to help us survive, not to make rational choices in volatile markets. Your brain seeks comfort and certainty; the market offers neither. So the mind starts to bend reality to feel safer in the moment, even if it harms returns over time.
The goal is not to eliminate emotions. The goal is to recognize when a bias is taking the wheel and have pre‑planned rules and safeguards that keep you aligned with your long‑term strategy.
Anchoring: Getting Stuck on the Wrong Number
Anchoring happens when you fixate on an initial reference point and let it overly influence later decisions. In investing, anchors often include the price you paid, a recent high, or a friend’s “target price.”
Examples of anchoring:
- Refusing to sell a losing stock because you want to “at least get back to break even.”
- Thinking a stock is a bargain only because it is down 30% from its high, without checking the fundamentals.
- Sticking to an old valuation metric in a business that has clearly changed.
The market does not care what price you paid. The only relevant questions are: What is this investment worth today and what is the opportunity cost of holding it versus something better?
Practical defenses against anchoring:
- When re‑evaluating a position, hide the purchase price and look only at current fundamentals and future prospects.
- Write a one‑page “investment thesis” when you buy, focusing on business quality, valuation, and risks. Review that thesis later instead of clinging to past prices.
- Use percentage portfolio rules: decide in advance at what conditions you will reduce or exit, based on business changes, not on your entry price.
Loss Aversion: The Pain of Losing Overshadows Gains
Loss aversion means losing $100 hurts more than gaining $100 feels good. This leads investors to make decisions aimed at avoiding pain rather than maximizing long‑term wealth.
Common patterns driven by loss aversion include:
Holding losers too long because selling would “lock in” the loss, while quickly selling winners to “take profits” and feel good. Over time, this can create a portfolio of weak holdings and too little exposure to strong compounding businesses.
It also encourages panic selling during market crashes, when prices feel unbearable. Yet history shows that selling after large market drops often converts temporary declines into permanent capital loss.
Practical defenses against loss aversion:
- Frame decisions in terms of future outcomes, not past mistakes. Ask, “If I had only cash today, would I buy this investment at its current price?”
- Use predefined asset allocation ranges for stocks, bonds, and cash. Rebalance periodically so you systematically buy after declines and trim after big rallies.
- Set a “cooling‑off” rule: during sharp market drops, you cannot sell anything for 48–72 hours. This pause reduces emotionally driven trades.
Overconfidence: Mistaking Opinions for Certainty
Overconfidence makes you believe your judgments are more accurate than they are. You may underestimate risks, trade too frequently, or take oversized positions in “high‑conviction” ideas.
Signs of overconfidence include:
Feeling sure that your forecast is right despite uncertain data. Believing you can “time the market” based on news or gut feel. Ignoring contradictory information because it threatens your belief.
Overconfidence often leads to excessive trading, which increases costs and taxes, and usually results in lower net returns compared with a steadier, rules‑based approach.
Practical defenses against overconfidence:
- Track your predictions. Write them down with dates and probabilities. Review them months later. This reality check usually shows how uncertain markets truly are.
- Set maximum position sizes and leverage limits. Do not allow excitement about an idea to bypass these rules.
- Use checklists before any major trade: thesis, downside scenarios, alternative uses of capital, and reasons you might be wrong.
Herding: Following the Crowd Into Trouble
Humans are social. In uncertain environments, we look to others for cues. In markets, this becomes herding: buying because others are buying, or selling because everyone seems scared.
Herding feels safe, but it often leads you to buy near tops and sell near bottoms. Popular assets already reflect the crowd’s enthusiasm in their prices. When sentiment reverses, those same assets can fall sharply.
Media headlines, social networks, and hype amplify herding. Seeing “everyone” talk about a stock or theme can create intense fear of missing out (FOMO), pushing you to abandon your plan at the worst possible time.
Practical defenses against herding:
Clarify your personal goals, risk tolerance, and time horizon in writing. A retired investor needing stability should not copy the aggressive strategies of a 25‑year‑old speculator online.
Before acting on popular ideas, ask yourself: “If nobody else talked about this, would I still be interested?” If the answer is no, refrain or keep the position tiny within your portfolio.
Confirmation Bias: Hearing Only What You Want to Hear
Confirmation bias makes you seek and trust information that supports your existing views while dismissing conflicting evidence. Once you own a stock or fund, you may read only bullish reports and ignore red flags.
This bias is dangerous because it reinforces poor decisions. The more you are invested—financially and emotionally—the harder it is to change your mind, even when the facts do.
Practical defenses against confirmation bias:
Whenever you research an investment, deliberately search for the strongest bear case. Read analysts or investors who disagree with you and summarize their arguments fairly.
Form a habit of writing both “Why I might be wrong” and “What would make me sell” before you buy. This pre‑commits you to respect new information, instead of rationalizing it away later.
How These Biases Damage Your Returns
The effect of behavioral mistakes compounds over time, just like returns do. Small emotional decisions add up: holding losers too long, selling winners too early, chasing hot themes, or sitting in cash during rebounds. The gap between market returns and investor returns can be surprisingly wide.
| Investor Behavior Pattern | Common Biases Involved | Typical Long‑Term Impact |
|---|---|---|
| Buying after big rallies, selling after crashes | Herding, loss aversion | Buy high, sell low; underperform market averages |
| Constant trading, reacting to every headline | Overconfidence, recency bias | Higher costs, more mistakes, lower net returns |
| Clinging to losers, quick profit‑taking on winners | Anchoring, loss aversion | Portfolio drifts toward weak assets over time |
| Ignoring negative information about favorite holdings | Confirmation bias | Delayed exits, larger drawdowns on bad ideas |
Building a Personal System to Tame Biases
You cannot switch off human nature, but you can design an investing system that reduces the damage. The key is to rely less on moment‑to‑moment feelings and more on clear rules and written processes.
Consider these steps to build your own bias‑resistant approach:
- Create an investment policy statement (IPS): Define your goals, time horizon, risk tolerance, asset allocation, and rules for rebalancing and withdrawals. This document becomes your anchor during emotional markets.
- Automate good behaviors where possible: Set up automatic contributions to investment accounts and automated rebalancing if your platform allows it.
- Limit portfolio checking: Constantly watching prices increases anxiety and bias‑driven reactions. Choose a schedule—monthly or quarterly—unless a major life event occurs.
- Use checklists for big decisions: Before any substantial trade, run through a short list addressing valuation, risks, alternatives, and potential biases affecting you.
Finally, cultivate humility. Markets are complex, and outcomes are uncertain. The most successful investors are not those who feel certain most of the time, but those who respect uncertainty and manage behavior better than others.
When you accept that biases exist, design safeguards, and stick to a consistent strategy, you move from reacting to the market to calmly navigating it. Over years and decades, that behavioral edge can be worth more than any hot tip or short‑term prediction.