Fixed vs Variable Interest Rates: Which Loan Is Right for You?
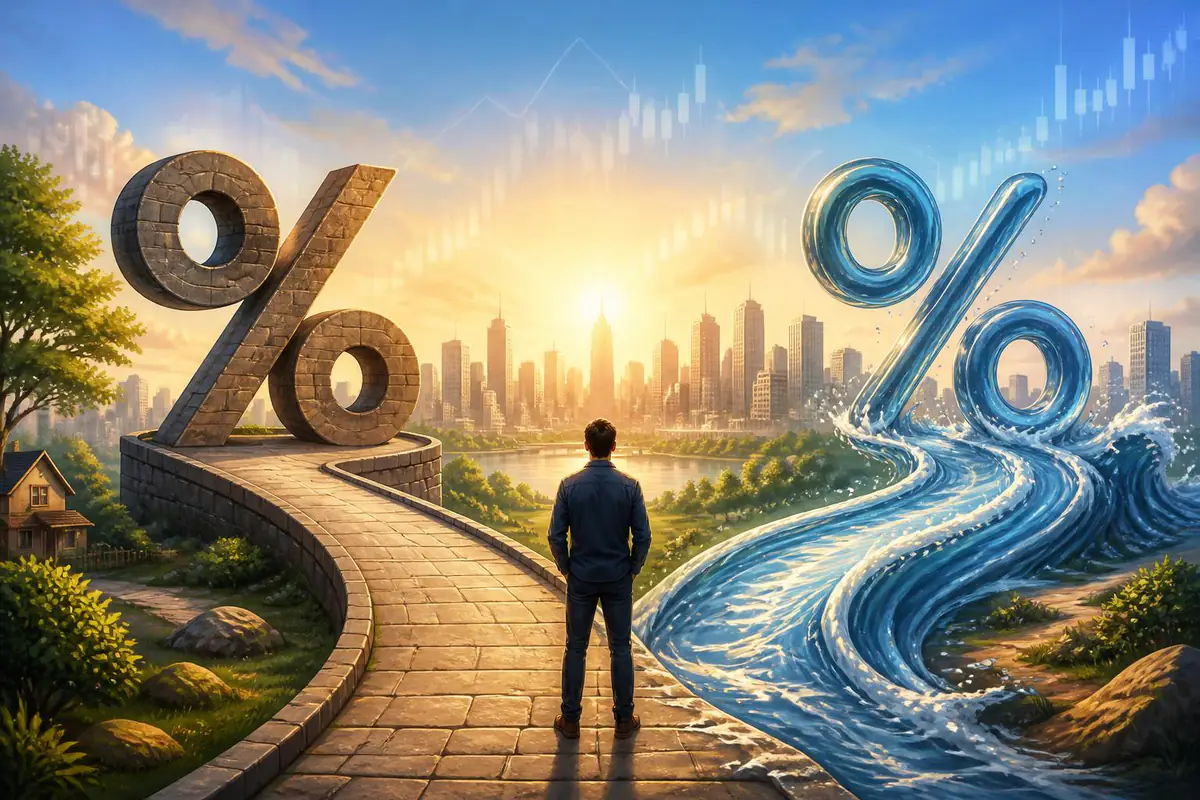
Choosing between a fixed and variable interest rate can feel like standing at a crossroads with no signposts. Both options can help you reach your financial goals, yet each carries different risks, advantages, and long‑term consequences.
Understanding how these rates work is not just for finance experts. It is a powerful way to protect your money, lower your stress, and make decisions that support your life plans, not just numbers.
What Is a Fixed Interest Rate?
A fixed interest rate stays the same for a set period, often for the entire life of the loan. That means your interest rate, and usually your monthly payment, will not change regardless of what happens in the wider economy.
Fixed rates are common in mortgages, car loans, and personal loans. When you choose a fixed rate, you are essentially buying certainty and payment stability. You trade the chance of paying less if rates fall for the security of knowing your costs will not suddenly rise.
What Is a Variable Interest Rate?
A variable (or adjustable) interest rate can change over time. It is often tied to a benchmark, such as a central bank rate or market index, plus a margin set by the lender.
This means your payments may increase or decrease as the benchmark rate moves. Variable rates can be attractive when interest rates are high but expected to fall, or when you plan to pay off the loan relatively quickly.
With a variable rate, you accept more uncertainty in exchange for the possibility of lower total interest costs over the life of the loan.
Key Differences at a Glance
To choose confidently, it helps to compare the most important features of each option side by side.
| Feature | Fixed Interest Rate | Variable Interest Rate |
|---|---|---|
| Rate movement | Does not change | Can go up or down |
| Monthly payment | Predictable and stable | May change over time |
| Budgeting ease | Very easy to plan | Requires more flexibility |
| Initial rate level | Often higher than variable | Often lower at the start |
| Risk of rising costs | Low | Moderate to high |
| Best for | Stability and long horizons | Flexibility, short horizons |
When a Fixed Rate Might Be Right for You
You might lean toward a fixed rate if your top priority is peace of mind. A steady payment can be especially valuable if your income is regular and you do not have much room in your budget for surprises.
Fixed rates can be a good choice if:
- You are planning to keep the loan for a long time, such as a mortgage you expect to hold for many years.
- Your budget is tight and a sudden payment increase would cause serious financial stress.
- You prefer predictability and want to know exactly what you will pay.
- You believe interest rates are more likely to rise than fall in the coming years.
By locking in a fixed rate, you are essentially buying insurance against future rate increases. That protection can be worth paying a slightly higher starting rate.
When a Variable Rate Might Be Right for You
A variable rate can be appealing if you are comfortable with some uncertainty and focused on minimizing costs, especially in the near term. The initial rate is often lower, which can reduce your early payments.
Variable rates can make sense if:
- You plan to repay the loan relatively quickly, such as a short personal loan or a mortgage you will refinance soon.
- You have enough financial cushion to handle potential increases in payments.
- You expect interest rates to fall or remain stable.
- You value flexibility and are willing to monitor market conditions.
Choosing a variable rate is not reckless if it is done thoughtfully. It can be a strategic choice when paired with a realistic plan and awareness of the risks.
Questions to Ask Before You Decide
Instead of starting with the interest rate, start with your life. The right loan choice should match how you actually live, earn, and spend.
Ask yourself:
- How stable is my income? If your earnings are predictable, you may be able to handle either option. If your income is irregular, a sudden jump in payments might be harder to manage.
- How long do I expect to keep this loan? The longer the loan term, the more valuable stability usually becomes.
- How much risk am I truly comfortable with? Imagine your payments increasing by 10–20%. Would that be manageable or overwhelming?
- What is happening with interest rates right now? While no one can predict perfectly, you can still consider whether rates are historically high, low, or average.
Being honest with yourself about these questions can do more for your financial wellbeing than chasing the lowest possible rate.
Practical Ways to Reduce Your Risk
Whether you choose fixed or variable, there are practical steps you can take to protect yourself and improve your outcome.
First, compare offers from multiple lenders. Small differences in rates and fees can add up to thousands over the loan term. Look beyond the interest rate alone and check total costs, including any penalties for early repayment.
Second, if you choose a variable rate, build a safety buffer. When you calculate whether you can afford the loan, test your budget as if the rate were one or two percentage points higher. If you can still manage the payment comfortably, you are less likely to be caught off guard.
Third, consider making extra payments when possible, especially early in the loan. Extra payments reduce your principal faster, which can lower total interest and give you more flexibility later. Always confirm that your lender allows additional repayments without heavy penalties.
Combining Fixed and Variable: A Middle Path
Some loans allow you to split your borrowing between fixed and variable portions. For example, you might fix the rate on half of your mortgage and leave the other half on a variable rate.
This blended approach can offer a balance of security and opportunity. You gain some protection if rates rise, while still having the chance to benefit if rates fall. It can be a practical choice if you are unsure which option to commit to fully but want to move forward instead of waiting.
Turning a Complex Choice into a Confident Decision
There is no universal right answer when it comes to fixed versus variable rates. The best choice is the one that fits your personal situation, your goals, and your comfort with uncertainty.
To move from confusion to clarity, focus on three core ideas:
First, understand how each option behaves over time, not just at the start. What happens if rates move sharply in either direction? How would that affect your daily life, not only your spreadsheet?
Second, align the loan with your timeline. If you expect major life changes—such as moving, changing jobs, or starting a family—choose terms that leave room for adjustment rather than locking you into rigid long‑term commitments you might regret.
Third, remember that your decision is not purely financial. Peace of mind has real value. If knowing your payment will not change helps you sleep better and plan more confidently, that stability is worth recognizing and respecting.
Empowering Yourself for Future Choices
The process of weighing fixed and variable rates can feel technical, but it is also an opportunity. As you learn how interest rates work, you build skills that will help with every major money decision you make in the future.
Each time you compare options, ask questions, and think ahead, you are practicing the habit of intentional, informed decision‑making. Over time, this habit can be more valuable than any single interest rate you secure today.
You do not need to predict the future to choose wisely. You only need to understand your own situation, be honest about your comfort with risk, and commit to a plan you can live with. From there, the loan you choose—fixed or variable—becomes not just a debt, but a tool that supports the life you are building.