Pros and Cons of Consolidating Your Debts Into One Loan
Debt can feel like a constant weight on your shoulders, especially when it’s scattered across multiple credit cards, personal loans, store cards, and overdrafts. Every account has a different interest rate, a different payment date, and a different minimum amount due. It’s no surprise that many people look to debt consolidation as a way to regain control.
Consolidating your debts into one loan can be a powerful strategy, but it’s not automatically the right move for everyone. Understanding the real benefits and hidden risks will help you make a confident decision instead of a desperate one.
What Is Debt Consolidation?
Debt consolidation means taking out a new loan to pay off several existing debts. You then have just one payment to manage instead of many. This can be done through a personal loan, a balance transfer credit card, a home equity loan, or other consolidation products offered by banks and lenders.
The key idea is to replace multiple high-cost debts with a single, hopefully cheaper, more manageable payment. But whether it truly helps depends on the loan terms and, just as importantly, your habits going forward.
The Main Advantages of Consolidating Your Debts
There are several reasons consolidation is so appealing, especially if your finances feel chaotic. Used thoughtfully, it can be a stepping stone toward long-term financial stability.
Simpler, More Manageable Payments
Juggling different due dates, statements, and amounts is exhausting. One of the biggest benefits of consolidation is streamlining everything into one clear monthly payment. This can lower the mental burden of debt and reduce the chance of missed or late payments.
For many people, simply knowing exactly what they owe each month—and when—is a huge relief. It becomes easier to plan your budget, track progress, and stay consistent.
Potentially Lower Interest Rates
If you have high-interest credit card debt, a consolidation loan might offer a lower rate. Over time, this can significantly reduce the amount of interest you pay and help you get out of debt faster, provided you keep making payments on schedule.
The potential savings come from replacing high variable rates with a fixed-rate loan. That said, this only works if the new loan’s interest rate and total cost (including fees) are truly better than what you’re paying now.
A Clearer Timeline to Becoming Debt-Free
Credit card debt can drag on for years if you only pay the minimum. Many consolidation loans come with a fixed term—say three, five, or seven years. This gives you a defined end date, which can be motivating and empowering.
Instead of feeling like your balance never moves, you’ll see steady progress as you pay down a structured loan each month. This structure can help you stay disciplined, especially if you pair it with a realistic budget.
Possible Improvement to Your Credit Over Time
Handled responsibly, consolidation may help your credit profile. Paying off maxed-out credit cards can improve your credit utilization ratio, and consistently making on-time payments on your new loan builds a stronger history.
This is not instant. At first, your score might dip slightly due to a hard inquiry and new account. But over the long run, consistent on-time payments and lower revolving balances can work in your favor.
The Hidden Drawbacks and Risks
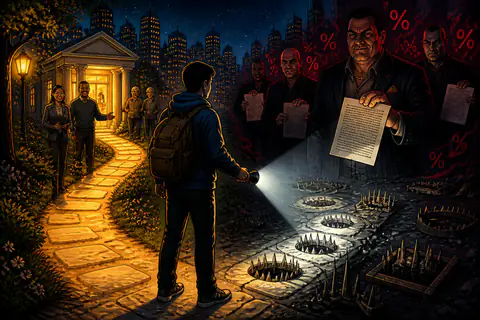
Debt consolidation is a tool, not a magic solution. If used without a plan, it can make things worse. Before signing anything, it’s crucial to understand the trade-offs and potential pitfalls.
Longer Repayment Periods Can Cost More
Many consolidation loans lower your monthly payment not because the deal is cheaper, but because they stretch your repayment over a longer period. Even with a lower rate, more years in debt can mean more total interest paid.
For example, paying off a balance over seven years instead of three might feel easier each month, but the overall cost of borrowing could actually increase. You need to compare total interest over the life of the loan, not just the monthly payment.
Risk of Falling Back Into Debt
One of the biggest dangers is clearing your credit cards with a consolidation loan, then running those balances back up. Without changing your spending habits, you can end up with the loan plus new card debt—leaving you in a deeper hole than before.
This risk is especially high if debt was caused by ongoing overspending, not by a one-time emergency. Consolidation must be paired with strong behavior changes and boundaries, such as limiting card use or closing some accounts.
Fees, Penalties, and Fine Print
Some consolidation loans come with origination fees, balance transfer fees, or early repayment penalties. These extra costs can eat into any interest savings you expect to gain.
Lenders may also offer a low introductory rate that later resets to something much higher. Before you commit, read all of the terms carefully and calculate the true total cost of consolidation, not just the teaser rate.
Potential Impact on Your Credit Score
Applying for a new loan usually involves a hard credit inquiry, which can temporarily lower your score. Opening a new account also affects your average account age, another factor in your credit profile.
While this short-term dip may be worth it if consolidation genuinely helps you move forward, you should still consider how it fits into your broader plans, like an upcoming mortgage or rental application.
When Debt Consolidation Makes Sense
Debt consolidation can be a smart move if certain conditions are met. It’s not only about numbers; it’s also about your mindset and readiness to handle money differently.
- You qualify for a loan with a lower interest rate than your current debts.
- You can comfortably afford the new monthly payment.
- You’re committed to not adding new debt once balances are consolidated.
- Your income is stable enough to maintain payments through the full term.
- You understand all fees, terms, and potential rate changes.
If most of these are true for you, consolidation might be a helpful tool in your financial toolkit, especially when combined with a solid budget and emergency fund plan.
Situations Where You Should Be Cautious
There are times when consolidating your debts into one loan may not be the best choice. Being honest about your situation can protect you from future stress.
Consolidation may be risky if:
- Your credit score is low, leading to high consolidation loan rates.
- Your income is unstable, making long-term commitments uncertain.
- Your main problem is overspending rather than interest costs.
- You’re nearing insolvency or considering more formal debt relief options.
In these cases, speaking with a qualified financial counselor or advisor may offer better alternatives, such as renegotiating payment plans or exploring other forms of structured debt relief.
Practical Steps to Decide If Consolidation Is Right for You
Before jumping into any new loan, take a calm, structured approach. This reduces the chance of emotional decisions driven by stress or fear.
Use the following simple comparison process to evaluate your options:
| Factor | Current Debts | Proposed Consolidation Loan |
|---|---|---|
| Total balance | Sum of all existing balances | New loan amount |
| Average interest rate | Weighted across your debts | Loan’s fixed or variable rate |
| Monthly payment | Total of all minimums | New single payment |
| Repayment period | How long to be debt-free | Loan term in months/years |
| Total interest cost | Estimated over remaining term | Estimated until loan is paid |
Seeing these numbers side by side can clarify whether consolidation truly saves money and fits your life, or whether it simply “feels” better because one payment sounds easier.
How to Make Consolidation Work in Your Favor
If you decide to consolidate, treat the new loan as a turning point, not just a reshuffling of balances. To get the full benefit, you need a clear plan for how you’ll stay on track.
Consider these practical strategies:
- Create a realistic budget that prioritizes consistent on-time loan payments.
- Limit credit card use, or keep one low-limit card only for emergencies.
- Set up automatic payments to avoid missing due dates.
- Build a small emergency fund so unexpected bills don’t go on credit.
- Regularly track your remaining loan balance to stay motivated.
These habits turn consolidation from a temporary fix into a genuine step toward long-term freedom from debt.
Turning a Financial Reset Into a Fresh Start
Consolidating your debts into one loan is neither inherently good nor bad. It’s a tool—powerful in the right hands, risky in the wrong context. Its success depends on careful math, honest self-reflection, and your willingness to change the patterns that created the debt in the first place.
If the numbers work and you use the opportunity to strengthen your financial habits, a consolidation loan can offer breathing room, clarity, and a path toward lasting financial stability and confidence. Paired with a solid plan, it can mark the moment your money starts working for you again, instead of the other way around.