Secured vs Unsecured Loans: Key Differences You Need to Know
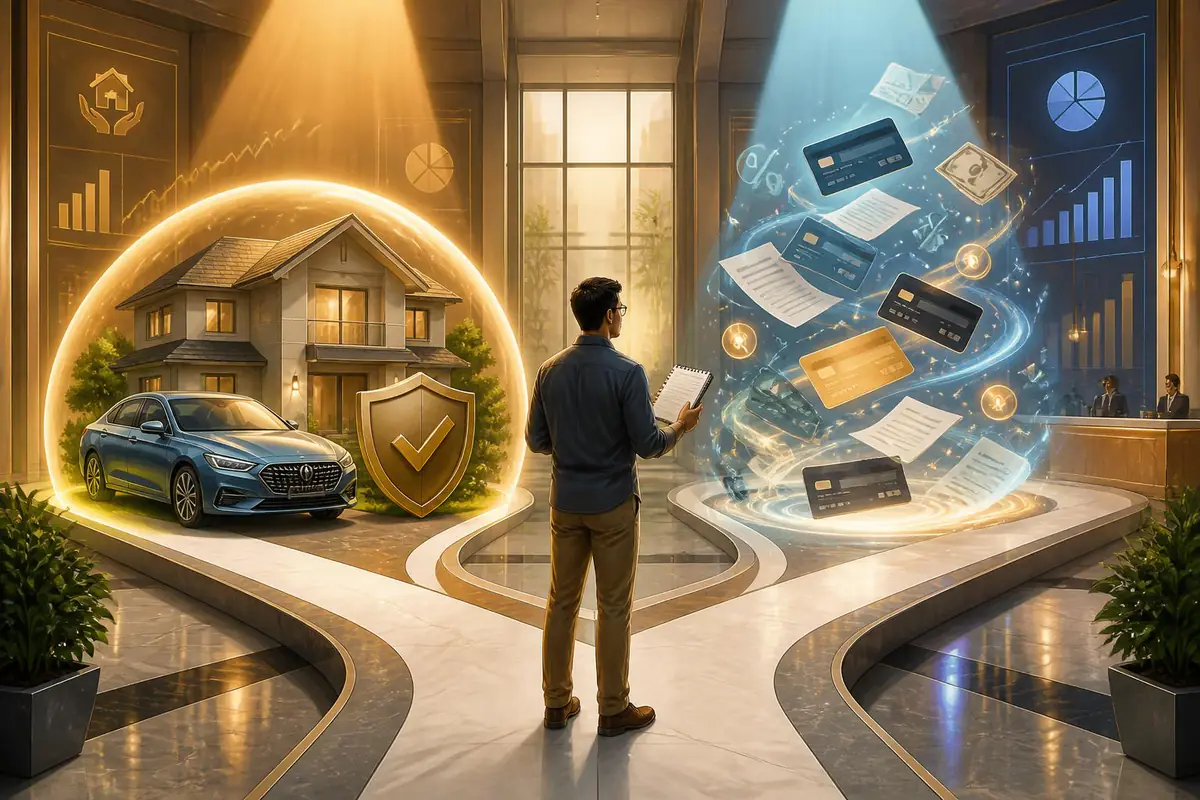
Choosing between a secured and an unsecured loan is one of the most important decisions you’ll make when borrowing money. The type of loan you choose affects how much you can borrow, the interest rate you pay, and what happens if you can’t repay.
Understanding these differences helps you protect your assets, avoid unnecessary risk, and choose the option that truly supports your financial goals instead of working against them.
What Is a Secured Loan?
A secured loan is backed by something valuable you own, called collateral. This gives the lender the right to take that asset if you stop making payments.
Common examples include:
- Mortgage loans (secured by your home)
- Auto loans (secured by your vehicle)
- Home equity loans or lines of credit
- Secured personal loans backed by savings
Because the lender has collateral, secured loans usually come with lower interest rates and higher limits than unsecured loans. They can be a powerful tool when used wisely—especially for large, long-term needs.
What Is an Unsecured Loan?
An unsecured loan does not require collateral. Instead, the lender relies on your credit history, income, and stability to decide whether to approve you and what rate to offer.
Common unsecured loans include:
- Personal loans from banks or online lenders
- Credit cards and lines of credit
- Student loans (typically not secured by assets)
Because the lender has no specific asset to claim if you default, unsecured loans usually charge higher interest rates and lower limits. However, they offer flexibility and less risk to your physical assets.
Key Differences at a Glance
The table below summarizes the main contrasts between secured and unsecured loans. Use it as a quick reference before you apply for any new credit.
| Feature | Secured Loan | Unsecured Loan |
|---|---|---|
| Requires collateral | Yes, backed by assets | No specific collateral required |
| Typical interest rate | Lower, due to reduced risk | Higher, due to higher risk |
| Loan amounts | Often larger, tied to asset value | Usually smaller, based on credit |
| Risk to borrower | Loss of asset if you default | Credit damage, collections, lawsuits |
| Approval factors | Asset value, income, credit | Credit score, income, history |
| Common uses | Homes, cars, large purchases | Debt consolidation, emergencies, small projects |
How Collateral Changes the Game
Collateral is at the heart of the secured vs unsecured debate. When you pledge an asset, you’re making a powerful promise to the lender: if I don’t pay, you can take this.
This changes the whole dynamic of the loan:
- You can often borrow more because the lender has something to recover.
- You may receive better interest rates and longer repayment terms.
- You carry the serious risk of losing that asset if your finances turn.
With unsecured loans, you don’t risk losing a specific item like your home or car. However, you still face real and lasting consequences if you fail to pay—credit damage, collection calls, wage garnishment, and legal action in extreme cases.
Interest Rates and Total Cost Over Time
One of the biggest practical differences is cost. Secured loans are cheaper on paper—but that doesn’t always mean they’re the right choice.
Typically, secured loans offer:
• Lower interest rates
• Longer repayment periods
• Smaller monthly payments on large amounts
Unsecured loans usually come with:
• Higher interest rates
• Shorter terms
• Higher monthly payments for the same amount borrowed
However, choosing a lower monthly payment can tempt you to borrow more or stretch repayment too long. That’s how people end up with decades of interest draining their income.
A practical approach is to look not just at the monthly payment but at the total cost you’ll pay over the full term. A slightly higher rate on a shorter unsecured loan may cost less overall than a low-rate secured loan stretched out for many years.
Risk: What Happens If You Can’t Pay?
This is where the difference becomes truly personal. With a secured loan, the lender can take the collateral if you default. That might mean foreclosure on a home or repossession of a car. For many people, that’s not just a financial blow—it’s a disruption to daily life and security.
With an unsecured loan, you won’t lose a particular asset directly to the lender. Instead, the lender may:
• Report late payments to credit bureaus
• Send the account to collections
• Sue in court to recover the balance
• Potentially garnish wages, depending on your location
Both paths are painful, but they’re different types of pain. Secured loans endanger specific property. Unsecured loans threaten your financial reputation and future options.
When a Secured Loan Can Be a Wise Choice
A secured loan can be extremely useful when used with intention and clear boundaries. It may be a good fit if:
- You’re buying a major asset (like a house or car) that will serve you for years.
- You need a large amount, and unsecured options are too expensive.
- You have a stable income and realistic confidence you can repay.
- You understand and accept the real risk of loss if things go wrong.
Secured loans can also help rebuild credit. For example, a small loan secured by savings or a certificate of deposit can show positive payment history, often at a lower rate than unsecured bad-credit options.
When an Unsecured Loan Might Be Safer
Unsecured loans may be better when you want flexibility and protection for your essential assets. They can be a smarter choice if:
• You’re covering short-term needs like medical bills or small home repairs.
• You don’t want to risk losing your home or car.
• You plan to pay the loan off quickly to limit interest.
• You have strong enough credit to avoid punishing rates.
An unsecured personal loan can also be a tool for debt consolidation and clarity, rolling multiple high-interest credit card balances into one fixed payment with a clear end date. The key is to avoid running up new card balances while paying off the loan.
Practical Steps Before You Decide
Before signing for any secured or unsecured loan, pause and walk through a few practical checks. These steps can save you money, stress, and regret.
Ask yourself:
• What exactly am I buying or solving with this loan?
• Is this expense urgent, or can it wait?
• What happens to my life if I lose the collateral?
• Can I comfortably afford the payment if my income drops?
Then, compare specific offers:
• Interest rate and whether it’s fixed or variable
• Total cost of the loan over time
• Fees, penalties, and prepayment rules
• Term length and impact on your monthly budget
If possible, build a small safety net before taking on new debt. Even a few weeks’ worth of expenses in savings can make the difference between a temporary setback and a crisis if something unexpected happens.
Using Loans as Tools, Not Traps
Loans themselves are neither good nor bad—they’re tools. A hammer can build a house or break a window. In the same way, both secured and unsecured loans can either move you closer to your goals or pull you away from them.
Use secured loans for large, essential assets that build long-term stability, and only with full awareness of the risk. Use unsecured loans for shorter-term needs, emergencies, or consolidating debt—with a clear plan to pay them off quickly.
Most importantly, give yourself permission to slow down before signing. Ask questions. Read the fine print. Calculate the real cost. Protecting your financial future is not about perfection—it’s about making calm, informed choices today that your future self will thank you for.